Wednesday, June 5, 2013

Dangerous Divergences Between Bonds and Stocks

By: Gary_Dorsch

It all seems so surreal. After being mesmerized by the Fed’s hallucinogenic “Quantitative Easing,” (QE) drug, and seduced by the Fed’s Zero Interest Rate Policy (ZIRP), and rescued by the Fed’s clandestine intervention in the stock index futures market, for the past 4-½-years, it’s easy to forget that there was once a time when the Fed’s main policy tool was simply adjusting the federal funds rate. It’s even harder to recall that two decades ago, the Fed’s raison d’ĂȘtre was combating inflation, whereas today, the Fed’s main mission is rigging the stock market, and inflating the fortunes of the wealthiest 10% of Americans.

“The central bank’s purpose is to get ahead of the inflation curve,” declared Wayne Angell, one of the seven governors of the Federal Reserve on June 1st, 1993. Angell had a reputation as a Fed hawk, and he was pushing for a tighter monetary policy, even before an uptick in the inflation rate showed-up in the government’s statistics. “If we’re ahead of the curve, our credibility and the value of our money is maintained. Some of my economist friends tell me, ‘We don’t feel much inflation out there, but we feel better knowing that you’re worried about it.” Thus, there was a time when savers received a positive rate of return on their money.

Two decades ago, the Greenspan Fed was stacked with hawkish money men. And because their tenures lasted for 14-years, they felt immune to the winds of politics. Thus, if the Fed governors were to make unpopular decisions to hike interest rates, in order to bring inflation under control, or burst asset bubbles, so be it. Of course, it’s much different today - the Fed is stacked with addicted money printers that are beholden to the demands of their political masters at the Treasury and the White House. How did Fed policy swing so radically from Angell’s day – when Fed tightening meant lifting the federal funds rate and draining excess liquidity, to today’s markets, - where a small reduction in the size of the Fed’s massive QE injections is considered to be a tighter money policy?

The Treasury Bond Vigilantes, - is a nickname that was used to refer to a legendary band of renegade bond traders, who used to fire-off warning shots to Washington, by aggressively selling T-bonds in order to protest any monetary or fiscal policies they considered inflationary. The jargon refers to the bond market’s ability to serve as a brake on reckless government spending and borrowing. The last major sighting of the bond vigilantes was in Europe, as they wrecked havoc upon the debt markets of Greece, Ireland, Italy, Portugal, and Spain.

James Carville, a former political adviser to President Clinton famously remarked at the time that “I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody,” he remarked. However, the so-called T-bond vigilantes appeared to be dead and buried over the past few years, as the US-Treasury was able to borrow trillions of dollars, largely financed by the Fed at the lowest interest rates in history. Keeping the T-bond vigilantes on ice, is a key linchpin of the Fed’s Ponzi scheme, that’s used to inflate the value of the US-stock market and keep it perched in the stratosphere.

However, last month, (May ’13), something very strange began to happen. It looked as though the long dormant T-bond vigilantes were suddenly beginning to awaken from their slumber. Indeed, - the long-end of the US Treasury bond market suffered its worst monthly decline in 2-½-years, as yields jumped to their highest levels in 13-months. Ticker symbol TLT.N, - the iShares Barclays 20+ Year Treasury Bond fund lost -7% of its market value. It looked as though Wall Street’s bond dealers were whittling down their holdings of T-bonds, - acting upon insider information from the New York Fed, - that the biggest buyer in the T-bond market could soon reduce the size of its monthly purchases and thereby cause T-bond prices to fall. Interestingly enough, T-bond yields jumped �bps higher even though US-government apparatchiks said inflation was only +1% higher than a year ago.

During Greenspan’s tenure, the Fed would try to push T-bond yields higher, by lifting the overnight federal funds rate. But in today’s hallucinogenic world of QE, - near zero-percent short-term T-bill rates, and historically low bond yields, - if the Fed begins to reduce the monthly size of its T-bond purchases in the months ahead, - it could have the same effect as a quasi tightening. That’s because the Fed has so badly distorted and inflated market prices over the last few years. If the heavy hand of the Fed is gradually withdrawn from the marketplace, the big question is: what would it mean for the $21-trillion US-equity market?
The Bernanke Fed is coming under increasing criticism. On May 29th, the 85-year old icon of central banking, - the greatest warrior against inflation in US-history, - former Fed chief Paul Volcker waded into the debate over when the Fed should start unwinding its radical QE operation, arguing that the “benefits of bond-buying are limited and is like pushing on a string.” Volcker launched a scathing critique of the Bernanke Fed, inferring the central bank had become a serial bubble blower. “The Fed is effectively acting as the world’s largest financial inter-mediator. The risks of encouraging speculative distortions and the inflationary potential of the current approach plainly deserve attention,” he warned.

Volcker reminded the new breed of Fed lackeys that the central bank’s basic responsibility is to maintain a “stable currency,” and that it should unwind its reckless scheme of massively increasing the US-money supply and blowing bubbles in the stock market. “Credibility is an enormous asset. Once earned, it must not be frittered away by yielding to the notion that a little inflation right now is a good a thing, a good thing to release animal spirits and to pep up investment. The implicit assumption behind that siren call must be that the inflation rate can be manipulated to reach economic objectives. Up today, maybe a little more tomorrow and then pulled back on command. Good luck in that. All experience demonstrates that inflation, when fairly and deliberately started, is hard to control and reverse,” Volcker warned.

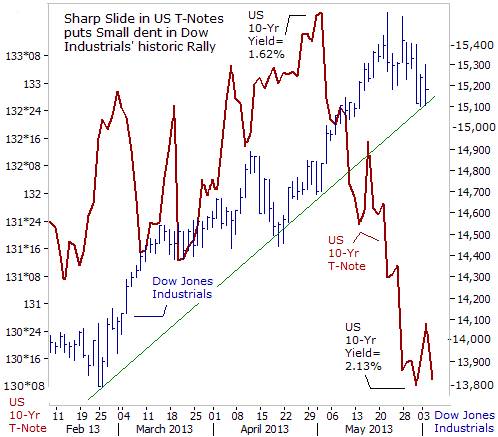
Last week, the Treasury’s 10-year yield climbed above the 2%-level, following Volcker’s remarks. The 85-year old Fed hawk still commands a lot of respect on Wall Street and his voice is not easy for the Fed’s rookies to tune out. The recent plunge in T-bond prices did trigger a knee-jerk sell-off in the stock market, that briefly knocked the Dow Industrials lower to the 15,100-level. But in a June 3rd note, Goldman Sachs (GS) released a message to the financial media, telling investors to remain calm amid the bond market sell-off. GS reiterated its Bullish stance on the US-stock market, - saying further gains lie ahead, and that S&P-500 companies have plenty of cash on hand, that can be deployed to offset the negative effect of higher interest rates, - by increase their dividends +11% this year and +10% in 2014. If correct, that would lift the S&P-500’s dividend yield to a meager 2.3-percent.
Still, yields on 10-year T-Notes increased by a half-percent in the month of May, including a jump of �bps on May 28th, - seen as a signal that the Fed’s would scale back its QE-injections. “A slowing in the pace of purchases could be viewed as applying less pressure to the gas pedal, rather than stepping on the brake,” said Kansas City Fed chief Esther George on June 4th. “It would importantly begin to lay the groundwork for a period when markets can prepare to function in a way that is far less dependent on central bank actions and allow them to resume their most essential roles of price discovery and resource allocation. I support slowing the pace of asset purchases as an appropriate next step for monetary policy. Waiting too long to prepare markets for more-normal policy settings carries no less risk than tightening too soon,” Ms George added. The Kansas City Fed chief cited signs of overheating markets, including margin loans at broker-dealers at a record $384-billion in April.

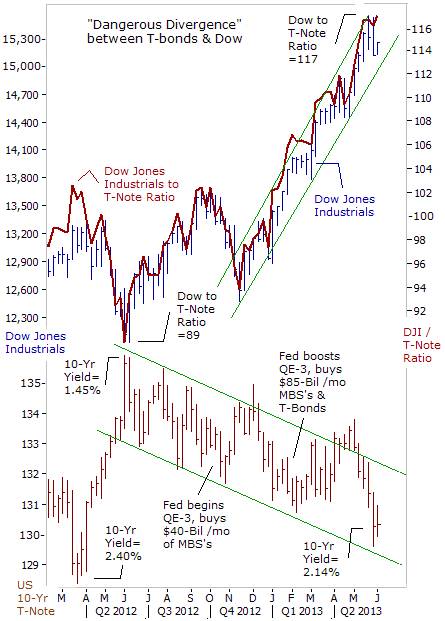
“We cannot live in fear that gee whiz the stock market is going to be unhappy that we are not giving them more monetary cocaine,” added Dallas Fed chief, Richard Fisher on June 4th. Still, many traders don’t believe that the Bernanke Fed could ever kick the QE-habit and act to tighten the money spigots. Since May ’12, traders have played the “Great Rotation” – shifting out of bonds and moving into stocks, seen as the best way to profit from the Fed’s radical schemes. However, there’s a good chance that going forward - the “Great Rotation” could morph into the “Dangerous Divergence.” If left unchecked, an extended slide in the T-bond market could trigger an upward spiral in the 10-year yield towards 3-percent, which in turn, would threaten to blow up the Fed’s Ponzi scheme.

Already, the ratio between the value of the Dow Industrials and 10-year T-note futures has reached the 116-level, - doubling from the 58-level – where it bottomed out in March ’09, and is within striking distance of its 2007 high. A last gasp rally in the US-stock market could be the catalyst that triggers a sharp sell-off in T-notes. At that point, the “Dangerous Divergence” could reach the breaking point, leaving the bond vigilantes to do their dirty work.

Minor Earthquake in Tokyo Bond market, - The recent sharp slide in US T-Notes was preceded by a tremor in the world’s second largest bond market in Tokyo. On April 4th, the Bank of Japan’s (BoJ) new governor, Haruhiko Kuroda, unveiled the most radical scheme ever, - designed to “shock and awe” Japanese bond traders into complete submission. The BoJ said it would double the amount of yen in circulation over the next two years, in order to whip-up inflation in the world’s third largest economy. The BoJ said it would trump the Fed, by printing ¥7-trillion each month, to be used to buy Japanese government bonds (JGB’s).

The BoJ was certain that it could continue to arm-wrestle Japanese banks and persuade its loyal citizens into buying 10-year JGB’s at yields of less than 1%, even as the BoJ says its aim is weaken the value of the Japanese yen, increase the costs of imports, and increase the consumer inflation rate to +2%. In other words, the BoJ expects investors to lock in negative yields for the next ten years. However, the gambit began to backfire, when yields on 10-year JGB’s rebounded from a historic low of 0.315% and surged to as high as 1% on May 23rd, - triggering a -7.3% crash in the Nikkei stock index. It was the Nikkei’s biggest one-day fall in 2-years, and kicked off an extended -17.5% slide to 13,050 by June 3rd.
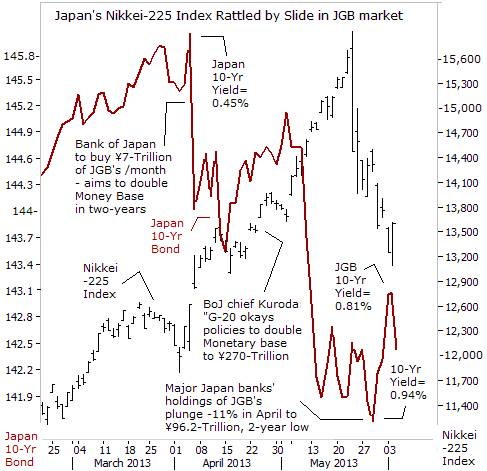
It was later revealed on May 30th, that Japan’s biggest banks decided to slash their holdings of JGB’s to ¥96.3-Trillion, in the month of April, - a sign that their selling played a major role in pushing up yields to 1%. Japanese banks were unusually rebellious, and dumped 11% of their JGB’s holding onto the BoJ’s balance sheet, fearing a major rout in the future. For the BoJ, trying to force JGB yields lower, when its trying to weaken the value of the yen and whip-up inflation, - is like trying to submerge a helium balloon under water.

If this exodus from the JGB market continues, it could blow apart the BoJ’s Ponzi scheme. Japan’s outstanding debt is equivalent to 245% of its annual economic output, and 92% of the debt has been financed by domestic savings. But this may not continue. A government panel’s draft report has reportedly warned that there is “absolutely no guarantee” that domestic investors will keep financing government debt. The BoJ has calculated that a rise in JGB yields of just 1% would lead to market losses equivalent to 10% of the core capital for the top Japanese banks, and 20% losses for the smaller regional banks.
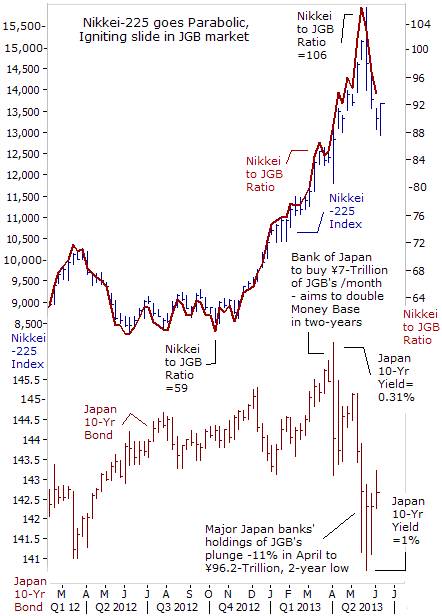
So far, the immediate impact of the BoJ’s Big-bang QE scheme has been a rapid and parabolic rise in Tokyo stock prices. These increases were fuelled by a frenzy of speculation by foreign traders. But rather than reflecting an economic recovery, the booming share markets are indicative of what the former-CEO of Citigroup, Chuck Prince, famously noted in July 2007, “As long as the music is playing, - you’ve got to get up and dance.” Nikkei Bulls are hopeful that the BoJ can keep the music playing, by boosting the size of its monthly JGB purchases if necessary. However, Tokyo cannot act in a vacuum - it would have to receive permission for an expanded QE scheme from its “Group-of-Seven” co-conspirators. And that’s unlikely.

“Stock markets are under the spell of QE,” In fact, both the BoJ and the Fed are in the crosshairs of the Bank for International Settlements (BIS), which warned on June 2nd, about the dangers of their ultra-cheap money policies that are driving up stock prices, despite worsening economic news. “Investors have ignored poor economic news as stocks have risen, leaving markets vulnerable to unsettling volatility and potential losses. Excessive monetary easing helped market participants to tune out signs of a global growth slowdown. But the rapid gains left equity valuations vulnerable to changes in sentiment, as witnessed in the recent bout of volatility in Japan,” the BIS warned.
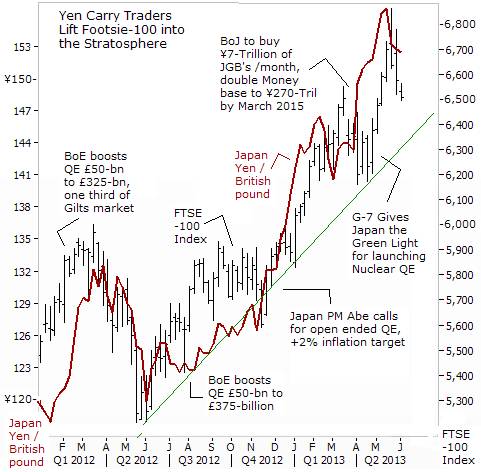
“Yen Carry” Trade lifts London Stock Exchange, “With yields in core bond markets at record lows, investors turned to lower-rated European bonds, emerging market paper and corporate debt to obtain yield. Abundant liquidity and low volatility fostered an environment favoring risk-taking and yen carry trade activity,” the BIS noted. Whether by extraordinary good luck, or by clever design, the FTSE-100 index didn’t need the help of the Bank of England’s (BoE) money printing machine, in order to climb sharply higher to the 6,800-level this year. Instead, the Footsie hitched a ride to the rising tide of liquidity flowing from Tokyo, - via the “yen carry” trade. It was a smart move by the BoE to kick the QE-habit back in November. The maneuver provided a solid foundation for the British pound to rally strongly against the Japanese yen, thereby encouraging carry traders to borrow cheaply in yen, and plow the cash in high yielding Footsie blue chips.

In its report, the BIS went on to say that stock markets “are under the spell of monetary easing to the point where negative news such as downbeat economic data doesn’t stop stocks from going up. Every time an economic indicator disappointed, traders simply took that as confirmation that central banks would continue to provide stimulus,” such as near zero percent interest rates or QE schemes that increase the supply of money in the economy.
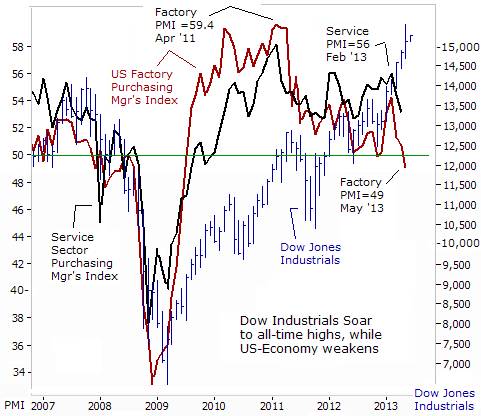
Such was the case on June 3rd - when the ISM’s index of US-factory activity fell to a reading of 49 in the month of May, down from 50.7 in April. That’s the lowest level in nearly four years and the reading under 50 indicates contraction. The unexpected drop in the headline figure reflected contractions in both the new orders index which fell to 48.8 in May from 52.3 in April, while the production index plunged to 48.6 from 53.5. Europe remains mired in recession and is buying fewer US-goods. In the first three months of this year, US- exports to Europe fell -8% compared with the same period a year ago. Despite the negative news, the Dow Jones Industrials soared to the 15,300-level, as traders reckoned the Fed would utilize it as an excuse to continue to print $85-billion per month of high octane liquidity.

BIS warns Bondholders – prepare for further losses, - However, Stephen Cecchetti, head of the BIS monetary and economic department, issued a warning to bankers and wealthy investors to prepare for an eventual normalization of interest rates that would cause additional losses for bond holders. “The losses, when they do occur, will be spread across banks, households and industrial firms.” He stressed it’s important that banks make sure their finances are strong enough before central banks end their QE programs and start raising interest rates. “Robust balance sheets with high capital buffers are the best ways to guard against the possible disruptions that this can bring,” he said.

On May 22nd, Bank of Korea Governor Kim Choong Soo also warned that when the Fed pullbacks from QE, it would spur risks worldwide from rising bond yields. “If the Fed begins to exit from quantitative easing policies, the world will be facing interest-rate risks, in terms of how much would bond yields rise,” he said. Also, IMF economists warned in May that a “potential sharp rise in long-term interest rates could prove difficult to control.”

Thus, while Goldman Sachs might be proven correct, and that another upward leg for the 51-month old Bull market still lies ahead, in the humble opinion of the Global Money Trends newsletter, it’s best to heed the advice of the legendary trader, Bernard Baruch, “I'll give you the bottom 10% and the top 10% of any move, if I get to keep the middle 80%.” In other words, for “Buy-and-Hold” investors, it’s a better strategy is to take advantage of any possible rally in the US-stock market to lighten up on long positions, rather than to add any new long positions at the tail end of a bubble.

See the original article >>

A Summer Stock Market Crash Scenario

By: Clif_Droke

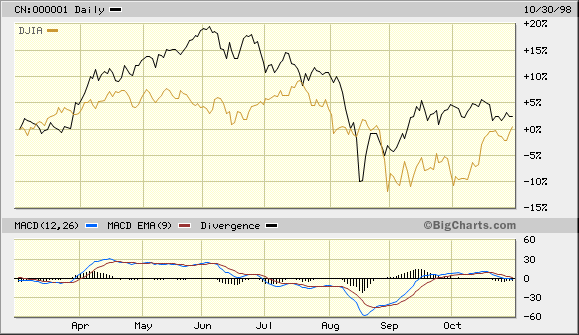
Despite the recent weakness, the broad market has displayed a fair amount of resilience in the face of rising interest rates and falling commodity prices. The charts even leave us with some hope that there will be one more rally to new highs in the coming weeks. But a growing list of problems also suggests the market could be setting up for a repeat of the 1998 mini-crash later this summer.


There are several parallels between now and the spring and summer of 1998 which led to the July-October decline. The year 1998 was an exceptionally strong one for U.S. equities for the first half of the year; that year also witnessed a strengthening domestic economy. Like this year, however, 1998 saw trouble begin overseas with global weakness reflected by falling commodity prices.

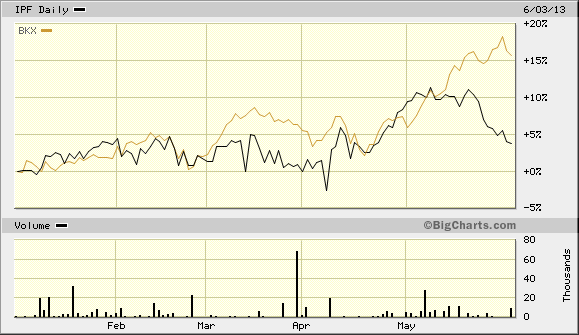
Another point of concern for the market this summer is the global financial sector. While U.S. banks are doing well due to improving balance sheets, foreign banks are lagging. The comparison between the SPDR International Financial Sector ETF (IPF, black line) and the Philly Bank Index (BKX, yellow line) illustrates this point.

As go the banks, so goes the broad market is the old saying. This applies to foreign banks as well, for as we’ve experienced many times in the past, weakness in foreign markets sooner or later always spills over into U.S. equities, a’ la 1998.


The U.S. stock market sell-off of ’98 was also preceded by late spring weakness in the Chinese stock market. In June the Shanghai Composite Index topped out several weeks ahead of the Dow Jones Industrial Average and began a decline which continued until August. China’s stock market bottomed several weeks before the U.S. indices, once again affirming the leading indicator relationship that has typically existed between U.S. and Chinese equities.

This time around the China ETF (FXI) is showing exceptional weakness versus the Dow and S&P 500 indices. FXI has established a series of lower highs against the higher highs in the Dow and S&P. This could be warning of another coming period of weakness ahead later this summer.


Commodity price weakness was another thing that led to the late summer sell-off in 1998. Several major commodities, including oil and gold, were in declining heading into the summer of ’98 and the decline in commodities can’t be overestimated. Falling commodities prices are a sign of deflationary pressures, which in this case are being brought on by the 120-year cycle being in its final descending stage into 2014.


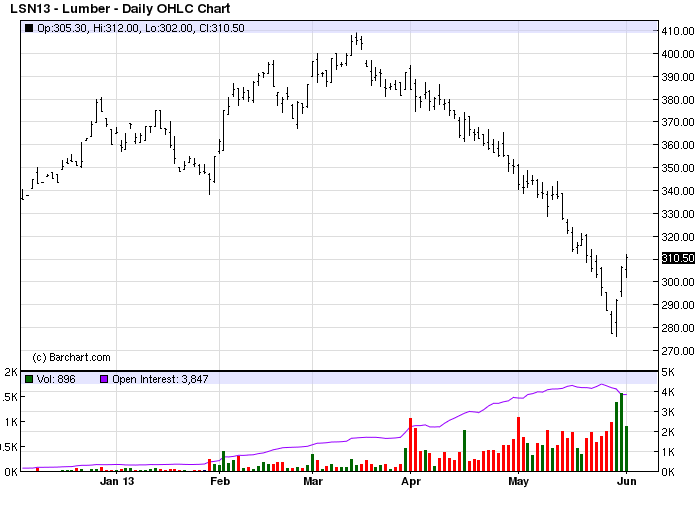
Low gold prices in particular are a sign that the market doesn’t have any inflation expectations for the economy in the foreseeable future. Moreover, with a highly touted housing market recovery underway it’s unusual to see lumber prices showing this much weakness (see chart below).

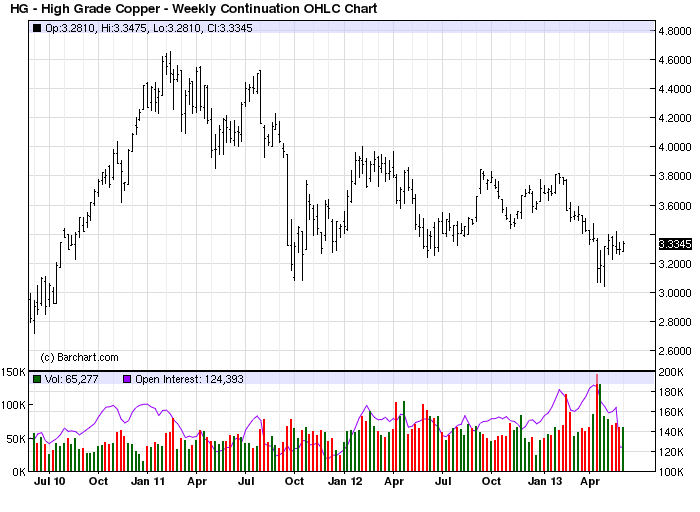
Copper prices are another important barometer of global economic health and right now copper is hovering near a two-year low.

In the 2013 forecast edition of the report published in early January we examined the Kress cycle “echoes” for this year. We specifically looked at the 6-year, 10-year, 30-year and 60-year patterns for stock prices for clues as to what the coming year might unfold. In each of the aforementioned “echo” years – 2007, 2003, 1983 and 1953 – stocks experienced a rocky period in the June-August period, with July and August being especially rough. This suggests that the coming July-August period could also be a rough one.

See the original article >>

Tuesday, June 4, 2013

The Threat to the Central-Bank Brand

by Mohamed A. El-Erian

NEW YORK – The “branding” of modern central banking started in the United States in the early 1980’s under then-Federal Reserve Board Chairman Paul Volcker. Facing worrisomely high and debilitating inflation, Volcker declared war against it – and won. In delivering secular disinflation, he did more than change expectations and economic behavior. He also greatly enhanced the Fed’s standing among the general public, in financial markets, and in policy circles.

This illustration is by Dean Rohrer and comes from <a href="http://www.newsart.com">NewsArt.com</a>, and is the property of the NewsArt organization and of its artist. Reproducing this image is a violation of copyright law.

Illustration by Dean Rohrer

Volcker’s victory was institutionalized in legislation and practices that granted central banks greater autonomy and, in some cases, formal independence from long-standing political constraints. To many, central banks now stood for reliability and responsible power. Simply put, they could be trusted to do the right thing; and they delivered.

As any corporate executive will tell you, brands can be consequential drivers of behavior. In essence, a brand is a promise; and powerful brands deliver on their promise consistently – be it based on quality, price, or experience. In some cases, consumers have been known to act on the strength of brand alone, even purchasing a product with relatively limited knowledge about it.

Indeed, brands send signals that facilitate the task at hand. In some special cases – think of Apple, Berkshire Hathaway, Facebook, and Google – they have also acted as a significant catalyst for behavioral modification. In the process, they often insert a wedge that essentially disconnects fundamentals from pricing.

Building on Volcker’s success, Western central banks have used their brand to help maintain low and stable inflation. By signaling their intention to contain price pressures, they would alter inflation expectations – and thus essentially convince the public and the government to do the heavy lifting.

In the last few years, however, the threat of inflation has not been an issue. Instead, Western central banks have had to confront market failures, fragmented financial systems, clogged monetary-policy transmission mechanisms, and sluggish growth in output and employment. Facing greater challenges in delivering desired outcomes, they have essentially pushed both policies and their brand power to the limit.

This is apparent in central banks’ aggressive emphasis on communication and forward policy guidance. Both have been used more widely – indeed, taken to extreme levels – to supplement the unconventional expansion of balance sheets in the context of liquidity traps.

Now, corporate executives will also tell you that brand management is a tricky affair. It is particularly hard to maintain or control your brand when popular sentiment overshoots.

This is what happened to Apple’s stock this year. As brilliantly explained by Guy Kawasaki in his book on the company, the brand essentially created “enchantment.” Extrapolating this into a market view that Apple could not only innovate continuously, but also fend off any and all competitors, investors took the company’s share price to dizzying heights.

Elsewhere in California, Facebook found its brand fueling enormous hype for the company’s initial public offering. Encouraged by investor excitement and indications of over-subscription, underwriters hiked the IPO’s price well above what they had first deemed reasonable. Issuing the stock to the public at an inflated price a year ago, the shares initially traded even higher.

In both of these cases, and in many others, brand power did more than lead to price behavior that was disconnected from fundamentals; it also caused a dangerous overshoot, which, when subsequently reversed, damaged the brand.

However powerful, brands cannot divorce pricing from fundamentals entirely and forever. Accordingly, and despite a significant market rally that has taken many individual stocks to record highs, Apple and Facebook currently trade at almost half their record levels. Their dominance and influence are no longer unquestioned.

Western central bankers should spend some time reflecting on these experiences. Some have actively encouraged markets to take the prices of many financial assets to levels no longer warranted by fundamentals. Others have stood by passively. Indeed, it seems that only retiring central bankers, such as Mervyn King of the Bank of England, are willing to raise concerns publicly.

This behavior is understandable. Central bankers are basically hoping that financial-market hype by itself can help pull fundamentals higher. The idea is that price action will trigger both the “wealth effect” and “animal spirits,” thus inducing consumers to spend more and companies to invest in future capacity.

Count me among those who worry about this situation. Far from a world of optimal policy, central bankers have been forced into prolonged reliance on imperfect approaches. From my professional vantage point, I sense a mounting risk of collateral damage and unintended consequences.

Market signals are more distorted, fueling resource misallocations. Investors are piling on more risk at increasingly elevated prices. Fundamentals-based investing is giving way to a frantic search for relative bargains in an increasingly overpriced financial world.

All this will not matter much if central banks live up to their reputation as responsible and powerful institutions that deliver on their economic promises. But if they do not – essentially because they are not getting the required support from politicians and other policymakers – then the downside will involve more than just disappointed outcomes. They will have materially damaged their standing and, consequently, the future effectiveness of their policy stance.

By extending well beyond their comfort zone, today’s central banks face unusual brand-management risks. Their prior ability to deliver on promises and expectations has made today’s financial markets take the forward pricing of the economy to levels that exceed what central bankers alone can reasonably deliver.

The implication is not that central banks should immediately halt their hyper-activism and unconventional measures. It is that they should be much more open about the inherent limitations of their policy effectiveness in current circumstances.

Western central bankers need to become much more vocal and, one hopes, more persuasive in placing pressure on politicians and other policymakers. Otherwise, risking major brand damage, they will end up adding yet another item to an already-overloaded plate of challenges for the next generation.

See the original article >>

The Truth About Wall Street Analysts & Why You Need Independence

by Lance Roberts

Turn on financial television or pick up a financially related magazine or newspaper and you will hear or read about what some stock analyst from some major Wall Street brokerage has to say about the markets or a particular company.   For the average person, and for most financial advisors, this information as taken as "fact" and is used as basis for portfolio investment decisions.  But why wouldn't you?  After all Carl Gugasian of Dewey, Cheatham & Howe just rated Bianchi Corp. a "Strong Buy."   That rating is surely something that you can "take to the bank", right?

Maybe not.

For many years I have been counseling individuals to disregard mainstream analyst and Wall Street recommendations due to the inherent conflict of interest between the major brokerage firms and their "retail" clients.  For individuals it is important to understand the relationship between your financial advisor, their firm and you.   When you hire a realtor to sell your house there is a clear understanding that the realtor will sell your house for a commission.  It is spelled out in advance in a contract and compensation is based on performance.   However, when it comes to financial advisors at major Wall Street firms the relationship is not quite as clear.

Major brokerage firms are big business.  Really big business.   As such they are driven by the needs of increasing corporate profitability on an annual basis regardless of market conditions.  This is where the conflict of interest arises.  For example, look at the annual EPS of JP Morgan from 1999 to present.  Despite two major bear markets, which led to investor losses of 50% each time, JP Morgan never had a year with negative earnings per share.  How is that possible?

jpmorgan-EPS

When it comes to Wall Street profitability the most lucrative transactions are not coming from servicing "Mom and Pop" retail clients trying to work their way towards retirement.  Wall Street is not "invested" along with you but rather use you to make income.  This is why "buy and hold" investment strategies are so widely promoted.  As long as your dollars are invested the mutual funds and brokerage firms collect fees regardless of market conditions.  While "buy and hold" strategies are certainly in their best interest - it is not necessarily yours.  However, these fees are a byline to the really big money.

In reality, Wall Street is focused on the multi-million, and billion, dollar investment banking transactions, such as public offerings, mergers, acquisitions and bond offerings which generate hundreds of millions to billions of dollars in fees for Wall Street each year.

However, in order for a firm to "win" that business from its major clients the Wall Street firms must cater to those clients.  In this regard, it is extremely difficult for the firm to gain investment banking business from a company that they have a "sell" rating on.  This is why "hold" is so widely used rather than "sell" as it does not disparage the end client.  To see how prevalant the use of the "hold" rating is I have compiled a chart of all the stocks that are ranked by major Wall Street firms and broken them down into the percentages that are ranked "Buy", "Hold" or "Sell."   See the problem here.

Hold-Code-Sell-060413

It is not surprising that there is just 7% of all stocks with a "sell" or "strong sell" rating.  It's just not good for business.

However, the conflict doesn't end just at Wall Street's pocketbook.  Companies depend on their stock prices rising because it is a huge part of executive compensation packages.  Corporations apply pressure on Wall Street firms, and their analysts, to ensure positive research reports on their companies with the threat that they will take their business to another "friendlier" firm.  This is also why up to 40% of corporate earnings reports are "fudged" to produce better outcomes.

So, what about the retail investor?  If Wall Street is more concerned about big business why do they need the retail investor at all?  This is where the conflict of interest becomes more clear.  Wall Street needs someone to sell their products to.  When Wall Street wants to do a stock offering for a new company they have to sell that stock to someone in order to provide their client, a company, with the funds that they need.   The Wall Street firm also makes a very nice commission from the transaction.

Generally, these publically offered shares are sold to the firm's biggest clients such as hedge funds, mutual funds and other institutional clients.  But where do those frims get their money?  From you.   Whether it is the money you invested in your mutual funds, 401k plan, pension fund or insurance annuity - at the bottom of the money grabbing frenzy is you.  Much like a pyramid scheme - all the players above you are making their money...from you.

In a recently released study by Lawrence Brown, Andrew Call, Michael Clement and Nathan Sharp it is clear that Wall Street analysts are clearly not that interested in you.  The study surveyed analysts from the major Wall Street firms to try and understand what went on behind closed doors when research reports were being put together.  In an interview with the researchers John Reeves and Llan Moscovitz wrote:

"Countless studies have shown that the forecasts and stock recommendations of sell-side analysts are of questionable value to investors. As it turns out, Wall Street sell-side analysts aren't primarily interested in making accurate stock picks and earnings forecasts. Despite the attention lavished on their forecasts and recommendations, predictive accuracy just isn't their main job."

The chart below is from the survey conducted by the researchers which shows the main factors that play into analysts compensation.  It is quite clear that what analysts are "paid" to do is quite different than what retail investors "think" they do.

Analyst-Survey-1-060413

"Sharp and Call told us that ordinary investors, who may be relying on analysts' stock recommendations to make decisions, need to know that accuracy in these areas is 'not a priority.' One analyst told the researchers:

'The part to me that's shocking about the industry is that I came into the industry thinking [success] would be based on how well my stock picks do. But a lot of it ends up being "What are your broker votes?"'

A 'broker vote' is an internal process whereby clients of the sell-side analysts' firms assess the value of their research and decide which firms' services they wish to buy. This process is crucial to analysts because good broker votes results in revenue for their firm. One analyst noted that broker votes 'directly impact my compensation and directly impact the compensation of my firm.'"

The question really becomes then "If the retail client is not the focus of the firm then who is?"  The survey table below clearly answers that question.

Analyst-Survey-2-060413

Not surprisingly you are at the bottom of the list.  The incestuous relationship between companies, institutional clients and Wall Street is the root cause of the ongoing problems within the financial system.  It is a closed loop that is portrayed to be a fair and functional system; however, in reality it has become a "money grab" that has corrupted not only the system but the regulatory agencies that are supposed to oversee it.  

The Rise Of Independence

In the past few years there is a change that is occurring which is the rise of independence.  Independent, fee only, financial advisors, private investment analysts, research and ratings firms have begun to infiltrate the system.   Over the last several years the independent RIA (registered investment advisor) channel is growing faster than overall industry as retail investors are "catching on" to Wall Street's game.  The "Occupy Wall Street" movement, while very misguided in its approach, was the first to ring the bell of the wealth gap between "Wall Street" and Main Street.

As more and more "baby boomers" head into retirement the need for high quality, independent, registered investment advisors will continue to grow.  The need for firms that do organic research, analysis and make investment decisions free from "conflict," and in the client's best interest, will continue to be in high demand in the years to come as more "boomers" leave the workforce.  While the "Wall Street" game is not likely to change anytime soon; the trust of Wall Street is fading and fading fast.  The rise of algorithmic, program and high frequency trading, scandals, insider trading and "crony capitalism" with Washington is causing "retail investors" to turn away to seek other alternatives.

Of course, two nasty bear markets certainly have not helped Wall Street.  Over the last several years the number of investment advisors has been steadily falling as individuals have taken back control of their own money.  While individuals believed that Wall Street was out to take care of them the real truth was markedly different.  Wall Street got rich while they got poorer.  Now, those same individuals are hiding in bonds to find some return along with safety.  The chart below shows the cumulative increase in bond funds versus stock funds as individuals seek safety over return.

ICI-Cumulative-Equity-Bond-060413

Today, probably more than ever, the tide is shifting for retail investors.  Those that want to venture into the shark infested waters of Wall Street on their own can certainly find plenty of tools, data and research online.  Wall Street has the clear advantage in this game with billions of dollars invested in programs that can manipulate prices, front run trades and move markets to their benefit.

However, an independent advisor can help level the playing field between Wall Street and you.  Provided they have the right team, tools and data they can spend the time necessary to manage portfolios, monitor trends, adjust allocations and protect capital through risk management.  That expertise, combined with advances in technology, now allows individuals the freedom not to be locked into finding an advisor that lives down the street but to find the best fit for their personal goals and objectives.  Today, top quality advisors have clients worldwide and can manage portfolios, communicate and service those clients effectively through technology.

The rise of independence is a good thing.  Hopefully, it will continue to take root and grow into a dominant force in the marketplace that can affect regulatory change in the future for a more fair, transparent and less conflicted financial market.  In the meantime, it is crucially importnat to start asking the right questions to figure out who is on your side.

See the original article >>

The Great Plunge is Coming

By tothetick

Are you ready for the next stock-market crash of the century? The Hindenburg Omen was spotted by eagle eyes on April 15th. It was confirmed by a sighting on May 29th. That gives us 40 days approximately before the market takes a plunge (apparently). That’s enough to spark fears on the market that we are in for a shaky time, but are those fears really justified and will the market plunge as the Hindenburg Omen predicts?

The Hindenburg is a technical analysis pattern that predicts highs and lows of the stock market based upon Norman G. Fosback’s High Low Logic Index (HLLI). It was invented by Jim Miekka in 1995. It’s used as a way of predicting big turndowns.

The Hindenburg has to meet four criteria and it is calculated using Wall Street Journal figures daily.

1. The sum of new 52-week highs and the sum of new 52-week lows must be equal or greater to 2.8% of the sum of NYSE issues advancing or declining on any given day.

2.  NYSE must be greater in terms of value than it was 50 days beforehand.

3. The McClellan Oscillator (money entering and leaving the market) must be negative on that day also (in other words, below zero equals a bearish market).

4. The 52-week highs must not be more than twice the 52-week lows (but the opposite does not hold).

The two sightings mean that the Hindenburg Omen has met the criteria.

There’s no point in my telling you that the market is not a science. The Hindenburg Omen tries to turn it into probability. But zero probability doesn’t exist as a zero. If it were zero, then it would be impossible. Zero improbability in Bayesian terms is just the measurement of probability as an indicator of confidence and belief in the market. You can predict as much as you like until the prediction doesn’t work. It’s human nature to want to try to find out before what will happen actually happens, but that we all know is impossible to do down to a T.

But, the last time the Hindenburg Omen caused nose-twitchy reactions and people running for the white-rabbit feet or other such lucky amulets fearing a drop in the market there was great talk of the Federal Reserve and fretting over their policies. That was back in August 2010 and it was Ben Bernanke’s QE statement that saved the day (maybe).

The same thing is going on now on the jittery market, with the fear that the US Federal Reserve’s pulling the plugs on bond-buying programs on the market will lead to a decline. But, can we really believe in the hocus-pocus, waving of the magic wand business that the Hindenburg Omen will come true? I could list a thousand omens that we should be wary of (according to some). But, I’m weary of living in the pseudo Middle Ages. It’s not the prediction of the Hindenburg that is going to trip the market up and make it fall flat on its face. If that happens, it will be down to something else.

The Dow Jones 17 months out of the last 20. That’s the longest steam ahead since 1951. Shouldn’t we be looking at other indicators rather than one that tries to predict the future? A 17-month rise is bound to come to an end at some time. If the unemployment figures released on Friday are better than expected, that could mean the Federal Reserve might take some drastic decisions. It’s that which might be worrying the market rather than the Hindenburg Omen.

To a certain extent it works, but if it worked every time, we wouldn’t be playing the market and we wouldn’t be sitting here surrounded by recession in the world at the moment. We would be living it up. The Hindenburg Omen is nothing more than a zeppelin of the past, which is not likely to work at all.

Although having said that, it has only got the market wrong twice out of all (and that’s a total of 8%) 25 sightings. But, it failed to spot the mild declines. Anything can work if we believe in it. We can arrange the data in any way we want to make it fit in with the requirements. Mild Hindenburg, strong Hindenburg, no Hindenburg. So you decide. It comes to something when we start trying to predict the market with a German commercial passenger-carrying airship. By the way, its crash remained a mystery for seventy-odd years until someone came along and gave the right explanation.

See the original article >>

Stock Market SPX, VIX Winding Up For Bearish Punch

By: Anthony_Cherniawski

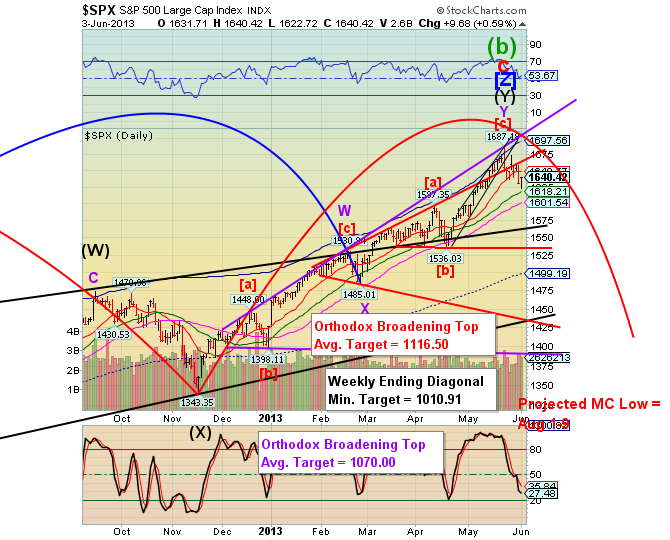
The SPX moves may appear disappointing at first glance. However, there is a lot of coiled up energy stored in these moves. All of these waves are impulsive and no matter how much they are being fought against, the waves are grinding down the opposition.

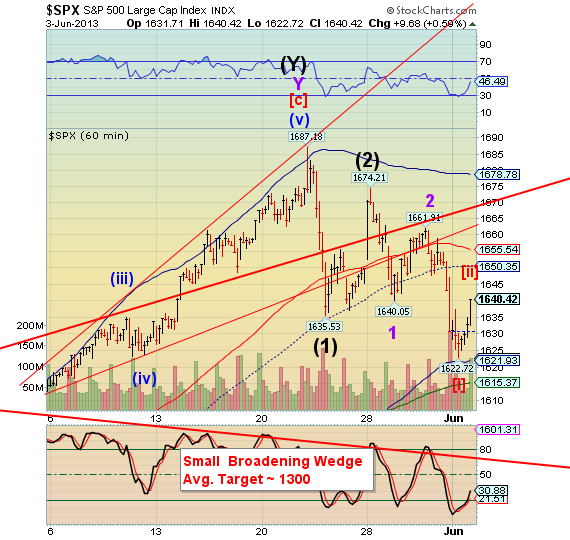
I have found that, when estimating the length of Wave threes, they are often a multiple of the cumulative wave ones. In this case, the cumulative value is 65 points, so the next wave down (assuming it’s a three) may have a minimum length of 130 points.

That may give SPX enough downside energy to break through both Intermediate-term support at 1618.21 and the 50-day moving average at 1601.54.

The downside target may be in the range of 1499.00 to 1510.00, below the smaller Orthodox Broadening Top. The bounce from that low may be contained by the Weekly Diagonal trendline, just below 1575.00. Remember, the SPX is still in throw-over territory in the weekly Ending Diagonal.

Once below the 50-day moving average, the speed of the decline may pick up. Those that are still bullish (there are many of them) may have a change of heart at that point.

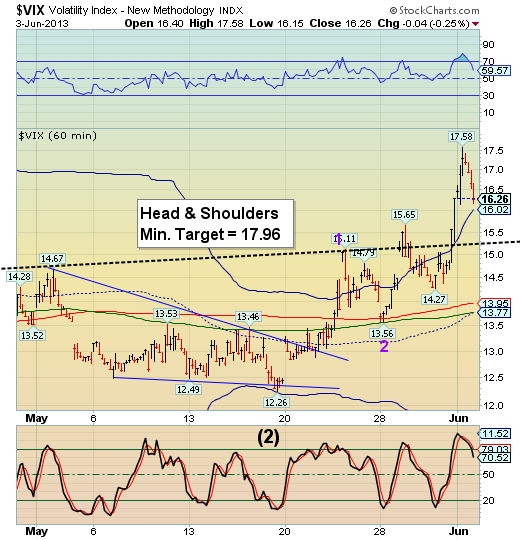
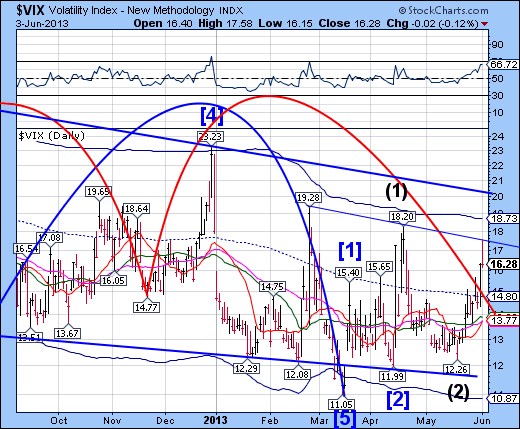
VIX has nearly made its Head & Shoulders target and it has not completed its pattern yet.

What seems to be holding the VIX from going higher at the moment is a small Diagonal formation that must be broken through. Once accomplished, the larger Diagonal formation must also be dealt with. The coiled up energy in the VIX may just do that very soon.

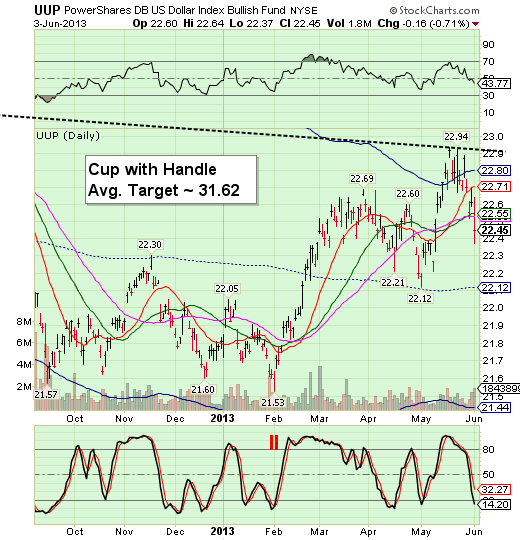
UUP is just completing a Trading Cycle low. The turn date for the new rally is tomorrow. There is a high correlation between the USD/UUP and the VIX. It appears that UUP/USD may have a breakout above the Lip of its Cup with Handle, which portends to be a very powerful move.

It just occurred to me that this may be the catalyst for the breakout in VIX and breakdown in SPX.

Good luck and happy trading!

See the original article >>

Follow Us