Friday, April 11, 2014

Prepare For Dollar Collapse With 33% Allocation To Gold - Rickards

by GoldCore

Today’s AM fix was USD 1,317.25, EUR 948.62 & GBP 785.71 per ounce.              

Yesterday’s AM fix was USD 1,321.50, EUR 953.19 & GBP 787.73 per ounce. 

Gold gained $6.90 or 0.53% yesterday to $1,318/oz. Silver rose $0.17 or 0.86% to $20.05/oz.  


Gold in U.S. Dollars - 1 Month  (Thomson Reuters)
Gold has eked out further gains today and is trading near its highest in 2 and a 1/2 weeks. It is on track for its best week in a month after equities fell sharply and due to renewed concerns that the U.S. Federal Reserve continuing their unprecedented ultra loose monetary policies.

Spot gold was steady at $1,322.10 an ounce by 1137 GMT, after three straight days of gains. The precious metal is up 1.4% for the week, having hit a high of $1,324.40 on Thursday - its highest since March 24.
Gold looks set to continue its recovery from last years battering due to still robust demand from India, China and increased safe haven demand due to much more pronounced geopolitical risk. The technicals have reversed and they and momentum are favouring gold again.
Bullion, already supported by significant tensions between the West and Russia, got a further boost on Wednesday when the Fed's March meeting minutes showed that the Fed are not keen on increasing interest rates straight after the wind-down of bond purchases.
Certain members of the Fed appear to realise that the economy and asset markets are now very dependent on near zero percent interest rates and continuing debt monetisation.


Gold in U.S. Dollars - 2 Years  (Thomson Reuters)
The Fed's tapering is largely priced into the gold market. What is not priced in is the real possibility that a weakening U.S. and global economy will lead to the Fed having to increase QE to previous levels and possibly even increase QE above the $85 billion level. The market is completely discounting this and we believe that this is a not negligible risk.

Quarter ends appear to be a good time to buy as seen on June 28th 2013, December 31st 2013 and now on March 31st, 2014.

These anomalies would appear to more than coincidental. They may be due to traders painting the tape or manipulation through HFT and computer trading. Goldman Sachs have been very vocal in their bearishness on gold at quarter ends. It is worth considering whether there is an attempt to "jaw bone" gold prices lower.

Silver continues to be favoured by contrarian investors who see it as oversold and very undervalued vis a vis other assets, including gold.

Gold Silver Ratio - 1996 to April 2014 (Quarterly) - Thomson Reuters

The gold silver ratio is now at 65, meaning that with one ounce of gold, one can buy 65 ounces of silver. The historic average throughout most of history is 15 to 1. Even in the 20th Century, the century in which silver was demonetised, the gold silver ratio averaged around 40.
GoldCore believe the ratio will revert to the mean average again in the coming years. There are a number of reasons that silver should revert to the long term historical mean but the two primary ones are the fact that geologically in the earth’s crust.  there are fifteen parts of silver to every one part of gold.

Secondly, the other reason is that silver is used in many industrial, medical and  technological applications today including photovoltaic cells in solar panels. Since the Industrial Revolution and in recent times, a huge amount of silver has been used up in industry. Silver is unlike gold in this regard. Rather it is akin to oil and other consumable commodities in this regard.
Thus, importantly silver is an attractive hybrid of commodity and precious metal used by investors as a store of value.

Thus, for every ounce of gold in the world today, there is less than 15 ounces of silver. Passionate silver buyers or “silver stackers” say the actual ratio of above ground refined silver to above ground refined gold is close to 1 to 1. Even if one uses a conservative number of 20 to 1, it shows that silver remains very undervalued versus gold. The supply demand equation in silver has gotten much more favourable in recent years and gets more favourable with every passing year.
For this reason we remain very confident that silver will surpass its 1980 record nominal high of $50/oz in the coming years. Indeed, the inflation adjusted high of $140/oz remains a viable price target in the long term.
Silver will in the coming years reward the patient, long term investor and buyer.

Prepare For Dollar Collapse With 33% Allocation To Gold
James Rickards, author of best selling book, Currency Wars and now The Death of Money: The Coming Collapse of the International Monetary System has done another great interview, this time with Erik Schatzker and Stephanie Ruhle from Bloomberg Television’s “Market Makers.

Topics covered included the risk of a deflationary collapse and depression, the risks of printing and creating too many dollars, the manipulation of gold and the importance of focusing on the long term and not just trying to make money in the short term but rather on preserving wealth.

DEFLATION AND THE RISK OF COLLAPSE

“The system is now larger than 2008 — make the system bigger and you’re going to have a bigger collapse …  we are further down the timeline,” Rickards warns.

“Are you going to believe me or the IMF? I have a little better track record.”

“The ultimate thesis is that deflation is the biggest problem in the world.”


“The world wants to deflate but central banks and governments cannot have deflation –  it increases the Debt-to-GDP ratio, destroys tax collection, creates bad debts and hurts the banks.”


“So central banks will do anything to avoid deflation. The way they do this is to print money. But if you print too much money then you’ll collapse confidence in the U.S. dollar.”


“The U.S. dollar is ultimately backed by confidence, as also said by Paul Volcker.”


“The FED is insolvent on a mark to market basis. I came to this conclusion himself, but insiders have also told me this privately  … they won’t say it publicly.”


“Money is a perpetual non-interest-bearing note issued by an insolvent central bank.
How long can that go on before people walk away from it?”


DEPRESSION

Rickards questions the consensus mantra of recovery and asserts that “we are in a depression and we have been in one since 2007.”


He admits that “if the FED had not done everything they’ve done, then things would have been much worse than they were in 2010. No question about that — unemployment would have been higher and growth would have been lower.


“But we should have been much stronger today. We should be having 7% growth now. We can’t have 7% for a long time, but we can for a short time while people come back into the workforce.

Instead we’re Japan — we’ve got 1.9% growth as far as the eye can see.


“So I would much rather have a little pain up front and then have robust growth”.


“Everyone wants a ‘V’ shape recovery, but you can’t have a ‘V’ unless you get to the bottom. We didn’t get to the bottom because the FED truncated the ‘V’.
WHY SHOULD PEOPLE CARE HOW MUCH MONEY THE FED PRINTS?

In answer to the assertion that investors should not care how much is printed, Rickards points out that  “the Fed’s safety net of printing has holes in it.”

“If the money printing could go on indefinitely then you would be right and I would agree with you but it cannot go on indefinitely.”

“The Fed could legally print more than the $4 trillion they’ve already created — $8 trillion, $12 trillion, $16 trillion. Some people say that they can do that — legally they can but my view is that that will destroy confidence at some point.”


“People say why doesn’t the FED just forgive the Treasury debt and make $4 trillion go away? They could do it legally but what would that do to the confidence?”

ECONOMY NOT RECOVERING

Rickards questions the assertion that the economy is recovering.

“The Fed said we had “green shoots” in 2009. Timothy Geithner declared a recovery in 2010. Nobody has a worse forecasting record than the FED. They do a one-year forward forecast each year … they have been wrong and off by orders of magnitude every year.”


When asked “who cares?”

Rickards says “listen to yourself … who cares about unlimited printing of money, who cares about bad forecasting, who cares about   destroying confidence.

“I care. I think we all should all care.”


THE CURSE OF THE 2 SECOND ATTENTION SPAN

People are investing based on what they think is going on right now, because they have “the curse of the 2 second attention span … So when the stock market is down 30% a couple of years from now,  you can kiss those investments goodbye.”


“WARREN BUFFETT IS BUYING HARD ASSETS AS FAST AS HE CAN”
“Look at Warren Buffett, he is getting out of cash and into hard assets as fast as he can — railroads and oil … Warren Buffett is buying hard assets as fast as he can.”


“I talk about this in Chapter 3 of ‘The Death of Money2, the FED is manipulating every market in the world with zero interest rates … I don’t like to be in manipulated markets …  I’d rather be in things that retain their value”.


RESULTS: GOLD VERSUS STOCKS
Bloomberg TV’s Erik Schatzker brings up a chart and points out that “March 9, 2009 was the bottom of the equity market. Since then the S&P has returned 170%. Gold is up 40% and hedge funds are up 20%.”
In answer to this question regarding gold’s underperformance versus stocks since stocks bottom in 2009, Rickards says, “this is exactly the chart I would expect to see if the market is manipulated by zero interest rates and margins sending stocks higher, and gold being manipulated lower.”


GOLD MANIPULATION

“The IMF sold 400 tonnes of gold in 2010. We know 200 tonnes went to India and Sri Lanka.Where did the other 200 tonnes go that they dumped on the market? They are funded by U.S. taxpayers but they are not being transparent.”


“If you manipulate stocks higher and manipulate gold lower, then you’ll see the chart from 2009 looking as it does.”
DATA MINING
Rickards points out that the chart is an exercise in data mining as they have  cherry picked the bottom for stocks.   “If you look back from 2000 you’ll see a very different chart”.


MAKE MONEY OR PRESERVE WEALTH
When asked what people should be doing with their money, Rickards says that he has “always recommended about 10% gold, not all in, not 50%”

“Do you want to make money or do you want to preserve wealth?”

Because you could make money today and lose it tomorrow.
Or you can preserve wealth.

We talk about the ‘old money’ in the U.S. , the 100 year money, and the ‘new money’. When you go to Europe, some of that money is 400 or 500 years old … and you say how did you survive the Thirty Years War, Napoleon and World War I etc and they will say …


A third — a third — a third …


One third gold.
One third art.
One third land.


And a little cash to run your jet and your yacht” he jested.


“That’s how you preserve wealth for the long run.

If you want a short pop go buy some stocks.”

It is a very interesting interview and we like the conclusion where he said investors can all make money in the short term but we can lose it just as easily.
Rickards does not expressly say one should put 33% of one’s wealth in gold but suggests that an allocation of between 10% and 33% would be prudent. In this regard, he echos Dr Marc Faber who suggested a 25% allocation to precious metals to us last week. Wealth preservation is something we have talked about since 2003. Indeed, our mission statement is to protect, preserve and grow the wealth of our clients.

The interview with James Rickards can be watched here: Should Investors Prepare for a Dollar Doomsday?

See the original article >>

Coffee heads higher

By Anthony Lazzara

U.S. stocks fell, after the Standard & Poor’s 500 Index yesterday posted its biggest gain in five weeks. Several Fed policy makers said a rise in their projection for the benchmark interest rate exaggerated the likely speed of tightening, according to minutes of their March 18-19 meeting released yesterday. The fewest number of Americans since before the last recession filed applications for unemployment benefits last week. The report showed China’s exports and imports unexpectedly fell in March.

Equities: E-mini S&P 500(CME:ESM14) is down 19.50 points to 1845.25, failing at the key 1865 level. We believe this market is headed lower, perhaps soon breaking below the key 1830 first support area. We would not be surprised to see 1800 sometime soon. We believe the negative surprise on the China data, coupled with the  prospect of steady tapering, is causing weakness in the S&P 500.

Bonds: The U.S. 30-year bonds(CBOT:USM14) are up 29 ticks to 134’11, likely due to inflows as equities decline. Also, the Russia Ukraine situation still seems to be stoking safe haven flows. If the SP500 approaches 1800 over the next few weeks, we could see more bond buying.

Currencies: The key theme recently is USD(NYBOT:DXM14) weakness. The USD is down 11 ticks to 79.44, well below the key psychological level of 80. The Euro is up 40 ticks to 138.91. We believe the Euro will hit 1.40 soon. The JUN14 Aussie is up again today, even in the face of negative China data. The Swiss Franc is up 49 ticks to 114.25. The Franc has had a quick and strong rally from its recent dip to 112.00.

Commodities: Coffee(NYBOT:KCM14) is up 3% to $208.30. We believe coffee has important resistance at the $2.20 area. Gold(COMEX:GCM14) is up $14 to $1320, right at a key moving average resistance level. Gold looks like it could head higher, however it does have some important resistance levels near here, starting with $1,330. MAY14 WTI crude oil is down $.39 to $103.22. There is overall bullishness in crude oil, but it could also be susceptible to a short term sell off back to $100, especially if the market believes the global economy headed by the United States and China are susceptible of a slowdown.

See the original article >>

EUR/CHF raising some near-term red flags

By Matt Weller

Volatility in the EUR/CHF has been subdued for years now, ever since the Swiss National Bank set an explicit floor at 1.20 in the pair. Despite the low volatility, the pair can still provide a useful barometer of risk sentiment in the market. Because the Swiss franc is still seen as a safe haven currency, the EUR/CHF tends to fall when traders are pessimistic about the global economy and rise when traders are feeling more optimistic. In fact, the price action over the last couple of days provides a clear example of that phenomenon: when traders were upbeat as yields and stocks started to break out midway last week, the EUR/CHF rose to a 2-month high at 1.2250. However, as equities and yields reversed back to the downside late last week and early this week, the EUR/CHF fell in turn.

At this point, the EUR/CHF is raising some near-term red flags on the outlook for global risk appetite. On a technical basis, the pair carved out a clear Evening Star* candlestick formation off resistance at the converging 100-day MA and 50% Fib retracement near 1.2250. This relatively rare 3-candle reversal pattern shows a gradual shift from buying to selling pressure and typically marks a top in the market. Confirming this signal, the pair’s RSI indicator just broke below its own rising trend line after finding resistance near the key 60 level. This price action suggests that the sellers still have the upper hand and portends a potential continuation lower over the coming days.

To the downside, bearish traders may look to target the lower 1.2100s, an area that marks the lows from early 2013, as long as the pair stays below its 100-day MA. More broadly, global equity and bond traders may want to exercise some caution unless EUR/CHF can regain its bullish mojo. Regardless, traders of all stripes should consider reserving some “chart space” on their trading computers for keeping an eye on EUR/CHF as a gauge of overall risk sentiment.

An Evening Star candle formation is relatively rare candlestick formation created by a long green candle, followed a small-bodied candle near the top of the first candle, and completed by a long-bodied red candle. It represents a transition from bullish to bearish momentum and foreshadows more weakness to come.

See the original article >>

Are We Losing Practical Life-Skills?

by Charles Hugh Smith

Poverty and lack of life skills are causally connected.

Are we as a society losing the basic practical life skills? Longtime correspondent Kevin K. recently submitted his informal survey of two basic skills: repairing a flat bicycle tire and changing a tire on a car.

I recently asked one of my tenants (a student at a top-tier public university) if she needed a pump when I saw that her bike tire was flat. She said that the tire would not hold air so I offered to let her use my pump, patch kit and tire irons to patch the tube. She had no idea what I was talking about and said she was going to bring it to a bike shop.
I offered to patch the tube for her (and did it in about 10 minutes) and asked if she knew how to change a tire on her Honda car and she said no. When I went home I asked my wife (a Stanford Grad with a Masters degree) if she could change the tire on any of our cars if she got a flat, she said "no". I asked if she could patch a bike tube and she said "maybe" (she said she learned how to replace a tube and air it up with a mini bottle of compressed air when working with a triathlon coach after college).
In the next week I asked 5 other guys and three other girls (all students at a top-tier public university) and of the 10 people I asked only two of the guys said they could change a car tire and fix a flat bike tire.
Kevin also recommended this blog entry, which I quote at length for reasons that will become clear as you read it:
Learning About Cars And Life Through An Old Man's Toolbox...
I am a "Millennial", just under the age of thirty. This is a title I have not quite embraced because of the negative connotations associated with the word, but it is something I have come to terms with accepting. A big part of the reason I take issue with being a Millennial is because I see people get completely lost in the simplest of basic life tasks because they cannot be bothered to learn a new skill or use practical self-sufficiency. Unfortunately, as a generation, many of us were not taught about the importance of life skills outside of formal education and social skills.
Going back even twenty years, people were a bit more self-sufficient for the most part. I remember more families back then having an actual dinner with each other a few days each week and take-out was something reserved for Friday nights. During the week, the family helped cook food or at least cleaned up the dishes afterward, but not us - not now. Did you know that most millennials spend more money on eating out than they do on groceries that could be used to cook our own food? Never in history has anything like that happened before and I can name far too many people around my age who cannot cook a meal for themselves. Self-sufficiency is eroding and this is only one example of many.
Those before us usually had some sort of backup plan for the rough patches they went through in life. Yet, we have not been taught to think that far ahead and I have seen too many people my age go after one goal, only to fail and then crash and burn because they have no idea of how to do anything else. They have no other skill set because most were not ever told to expect their world to possibly fall apart.
I have relied on the more mechanical examples of things we are capable of but choose not to embark on, but that is the most constant self-sufficiency model I have in my own life. I am not a technician, but I learned everything I know from necessity and research because I refuse to pay anyone to do anything I am capable of doing just as well on my own with a little research and practical education, but I know few people who hold that same mindset in my generation.
When I help someone with a task they are not very keen on, I would rather teach them what I know so they can retain it for the future. As an example, my friend's car had an issue and I figured out it was her alternator (read more about that here). She stood right beside me the entire time I was working on her car and I explained how everything worked as well as what I was doing through the entire process. When I needed a little assistance, she jumped right in and had no issue getting some dirt on her hands. Though I could tell it was a little taxing on her patience, the smile on her face when it was all back together made the whole thing worth it. She is an exception to what I most often see in our generation because she is never afraid to learn anything new, even though her chosen career is not even remotely close to parking lot automotive repair. I admire people like that. I admire those who are not afraid to learn something new.
I admire those who solve their own problems.
This is not a generational slam on Millennials: how many Gen-Xers or Baby Boomers can fix stuff when it breaks? How many maintain their own vehicles, homes, computers and appliances? How many are seeking out new life-skills to master?
In my view, our education system is self-serving, i.e. the goal of institutional education is to qualify the student to enter the next level of institutional education, rather than prepare students to create value and solve problems in the real world, which is the only source of premium available to labor, i.e. the only reason anyone will pay a human being rather than get the work done by software or robotics.
Only the wealthy can afford to have someone else fix their bicycle, walk and wash their dog, change the oil in their car, repair their house, etc. Practical skills enable an individual or household to lower the cost of living to the point that savings (capital accumulation) is possible. Practical skills are human capital, which is the means of production in a knowledge economy.

The Knowledge Economy's Two Classes of Workers (March 29, 2013)
In a very real sense, those with few practical skills are doomed to a zero-capital life unless they earn enough to pay somebody else to do everything for them, i.e. a minimum of $150,000+ a year, i.e. a top 10% household income. Even at that income level, people who can't do anything for themselves may not be able to save any money.
Poverty and lack of life skills are causally connected.
Science fiction author Robert Heinlein famously listed the skills of the generally competent in his book Time Enough for Love:

"A human being should be able to change a diaper, plan an invasion, butcher a hog, conn a ship, design a building, write a sonnet, balance accounts, build a wall, set a bone, comfort the dying, take orders, give orders, cooperate, act alone, solve equations, analyze a new problem, pitch manure, program a computer, cook a tasty meal, fight efficiently, die gallantly. Specialization is for insects."

I propose amending Heinlein's list for the modern era: The marginally competent person should know how to:
1. Look up how to fix something on the Web
2. Use WD-40
3. Get a bicycle chain back on the gears
4. Apply superglue without gluing their fingers together
5. Change the oil in a car
6. Replace a lockset
7. Troubleshoot network connections on a PC/laptop
8. Make a stir-fry meal using multiple fresh ingredients
9. Compose coherent instructions that explain how to do something useful
10. Keep a variety of plants alive and producing fruit, vegetables or flowers
This is obviously a very short list, but we have to start somewhere.
Of related interest:

Zen and the Art of Motorcycle Maintenance (March 15, 2007)
Self-Reliance II (March 16, 2007)

See the original article >>

This stock market needs a correction

By Jonathan Burton

Opinion: Be proactive, not reactive — and buckle up


The Financial Philosopher

SAN FRANCISCO (MarketWatch) — When the stock market becomes unmanageable – as it’s been lately — you have to manage expectations.

Easier said than done. With the S&P 500 /quotes/zigman/3870025/realtime SPX -0.47% down 2% on Thursday , and the Nasdaq /quotes/zigman/12633936/realtime COMP -0.53%   down 3%, anxiety grows and perspective goes.

What now? Contain your emotions. This market is in transition, and transitions are rarely as smooth as we would like. You have to find ways to handle change more skillfully. Not more easily, because change is hard. But competently, composed, and with the conviction that if you can’t do this yourself, there are trustworthy financial professionals who can help.

There’s an old truism about investing that a stock doesn’t know you own it and doesn’t care whether you make money or not. Yet after the stunning 30% return the S&P 500 gave investors in 2013, it’s been easy to welcome stocks back into the fold. That market meltdown is so 2008; all is forgiven, please come home.

Instead, stocks have been unforgiving. Another old adage -- “Don’t confuse brilliance with a bull market”-- also applies now. Anyone can make money in a bull market. Investors prove themselves when they can outsmart the average bear.

That’s your job now. The slide in highflying biotechnology /quotes/zigman/85342/delayed/quotes/nls/ibb IBB -1.02% and other momentum stocks could trigger a real correction for the S&P 500 – that painful 10%-plus tumble which hasn’t been experienced since the summer of 2011.

So pay attention to investors who’ve seen it all before. Retired market technician Bob Farrell is always a good resource. His 10 “Market Rules to Remember” offers investors a reality check on stocks, bonds and their money.

For example, consider Farrell’s Rule No. 6: “Fear and greed are stronger than long-term resolve.”

What Farrell is saying is that investors can be their own worst enemy. The counter to fear and greed is self-control. Don’t believe it’s different this time. Don’t chase the hottest sectors and stocks. Keep enough cash on hand so you’re not dumping stocks at fire-sale prices when pessimism is high.

In this way, you can be ready to buy when others are selling and scoop up the bargains from your stock-market shopping list (Always have a shopping list.)

Remember, Mr. Market is mortal. “There are no new eras -- excesses are never permanent,” Farrell noted in another of his famous rules.

In other words, wait for your pitch. Diversify your portfolio’s risk to a level that is true and honest, and then the stock market’s stumbles can become opportunities.

See the original article >>

Natural gas has largest storage withdrawal on record

by U.S. Energy Information Administration 

Overview:

(For the Week Ending Wednesday, April 9, 2014)
  • Spot prices rose slightly at most hubs for the report week (Wednesday, April 2, to Wednesday, April 9) and went up significantly at the benchmark Henry Hub, following declines the previous week. The Henry Hub spot price rose from $4.35/MMBtu last Wednesday to $4.66/MMBtu yesterday.
  • At the New York Mercantile Exchange (Nymex), the May 2014 contract increased from $4.364/MMBtu on Wednesday to $4.586/MMBtu yesterday.
  • Working natural gas in storage rose to 826 billion cubic feet (Bcf) as of Friday, April 4, according to the U.S. Energy Information Administration (EIA) Weekly Natural Gas Storage Report (WNGSR). A net storage injection of 4 Bcf for the week resulted in storage levels 50.7% below year-ago levels and 54.7% below the 5-year average.
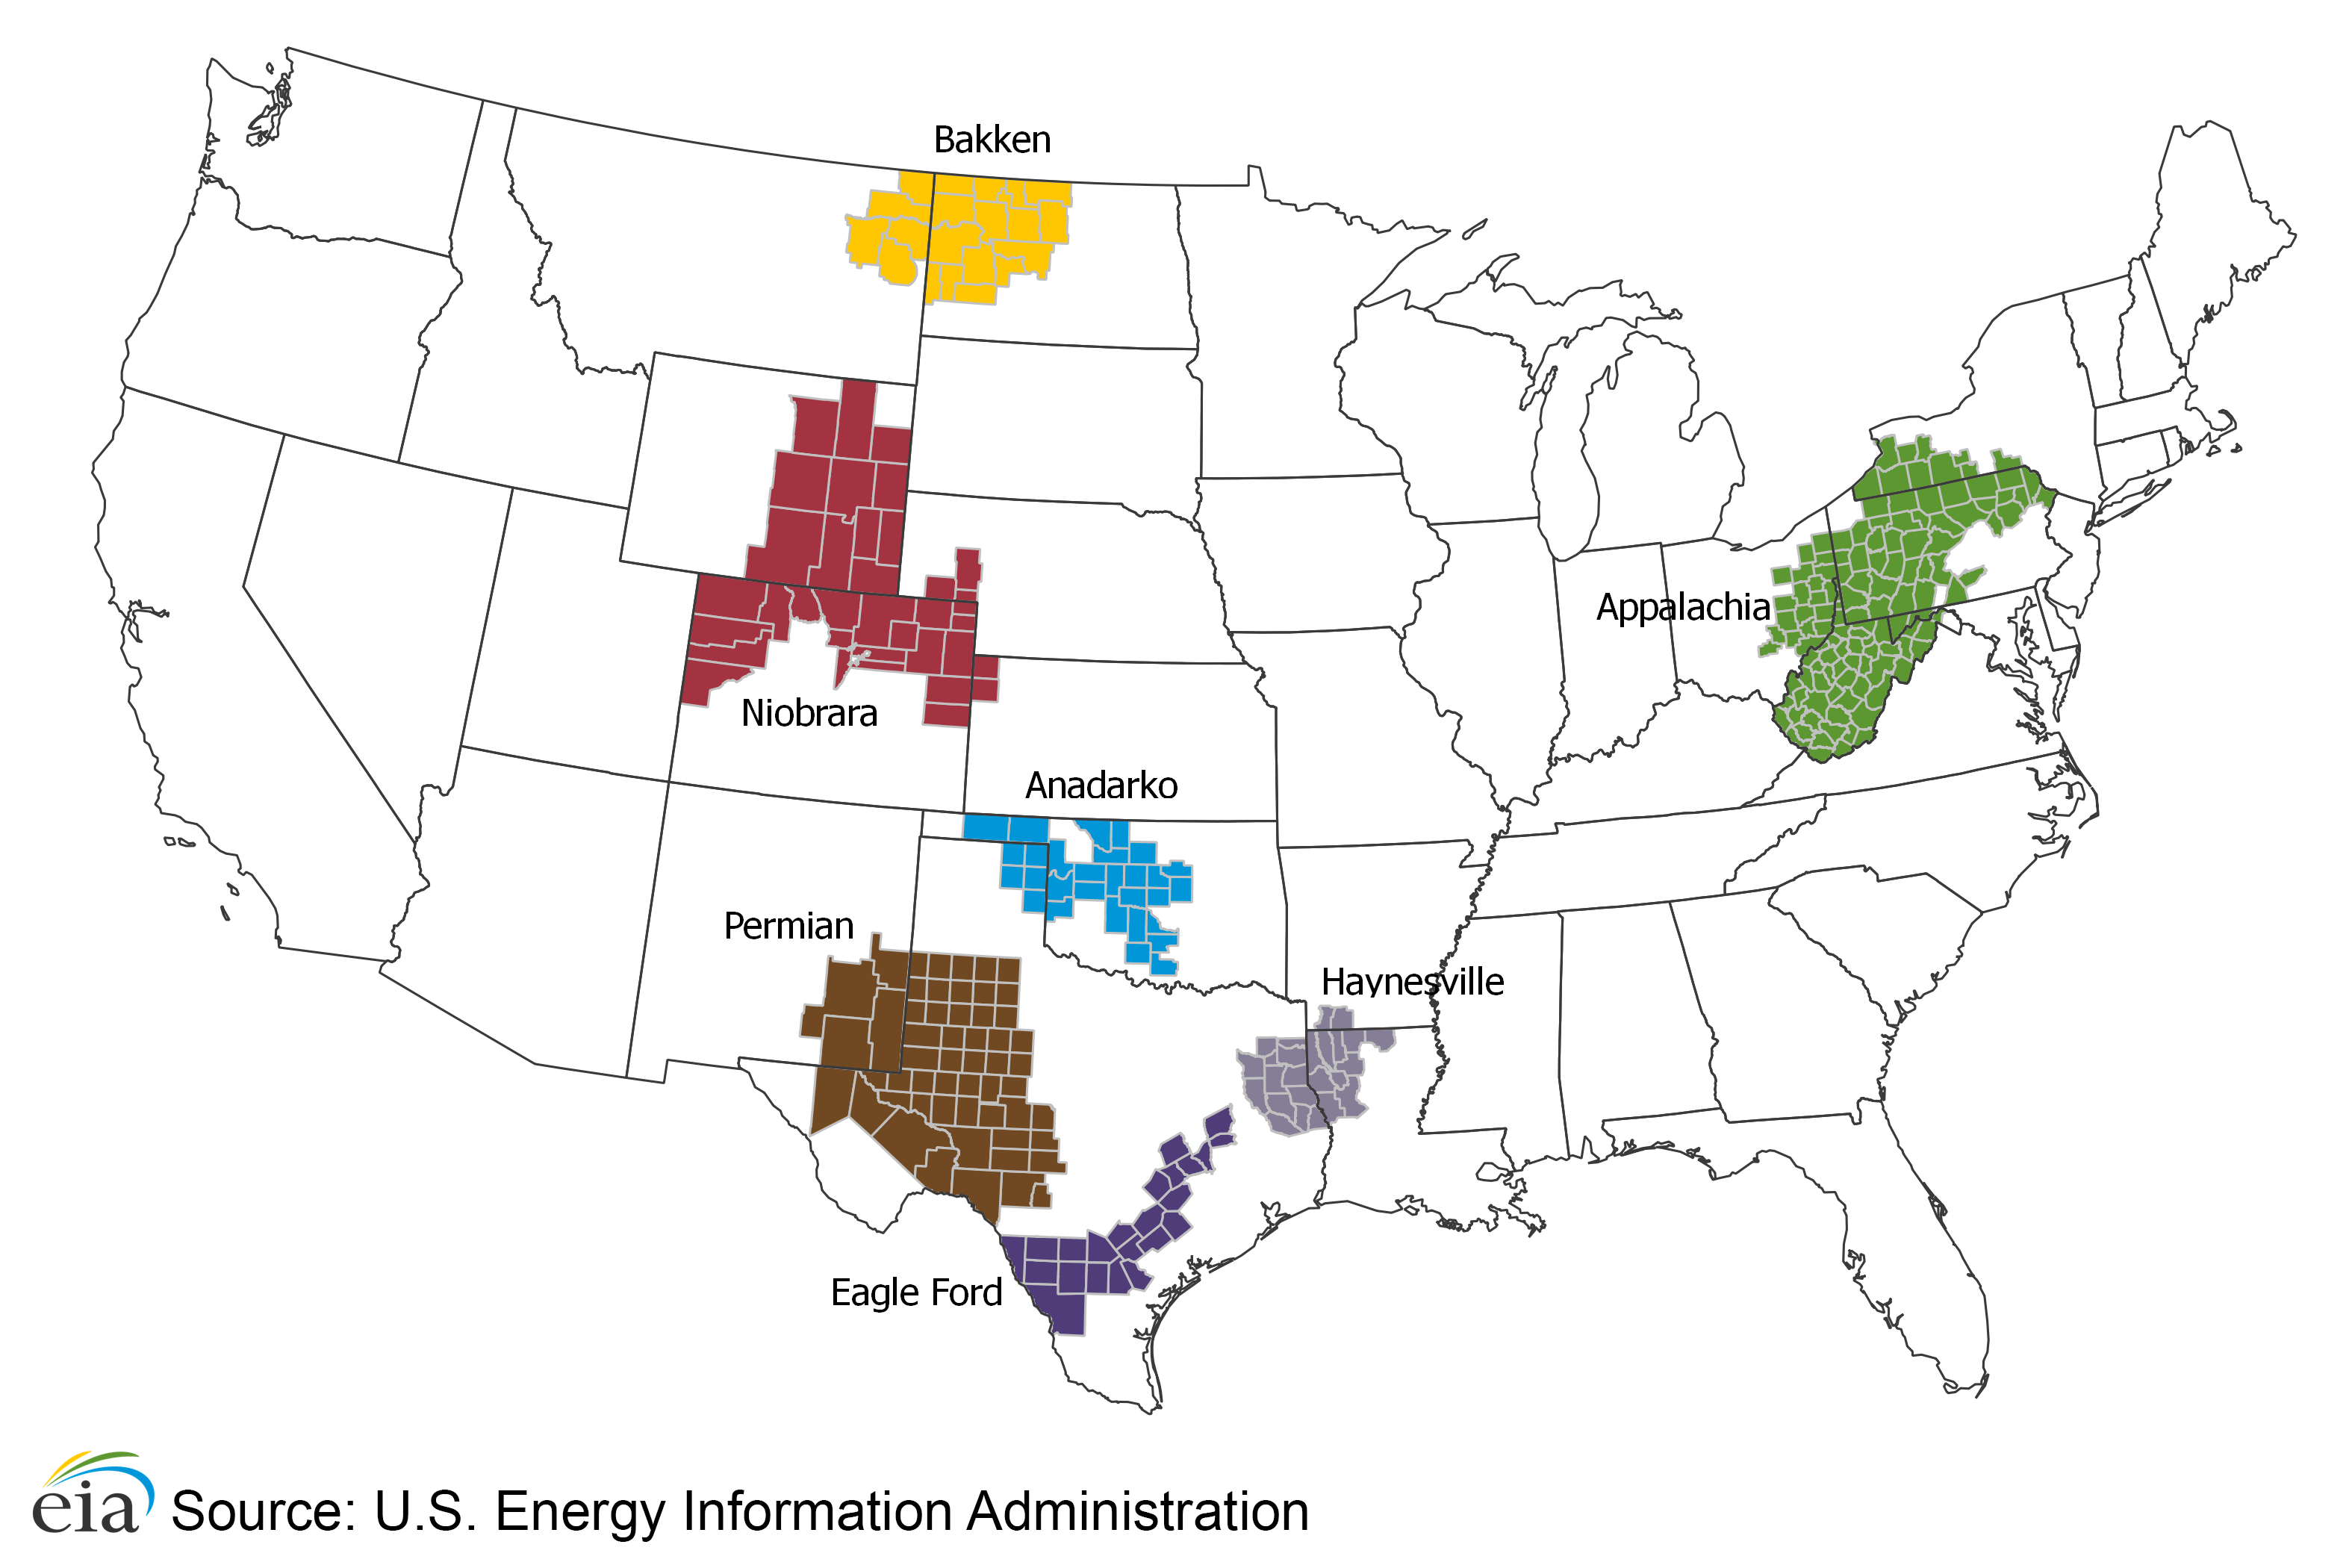
  • The total rig count was 1,818 as of April 4, an increase of 9 from the previous week, according to data from Baker Hughes Inc. The natural gas rig count decreased by 2 rigs to 316, while the number of oil-directed rigs rose by 11 to 1,498. Since the beginning of 2014, the gas-directed rig count has decreased by 56, with the biggest declines at the Eagle Ford Shale in South Texas (-15), and the Woodford Shale in Oklahoma and Texas (--10). The oil-directed rig count increased by 120, with biggest increases at the Permian Basin in West Texas and eastern New Mexico (61), and the Eagle Ford (11).
  • A 2% rise in the price of propane, from $11.48/MMBtu to $11.71/MMBtu, caused the weekly average natural gas plant liquids composite price to increase for the second week in a row. The composite price rose this week (covering March 31 through April 4) by 0.2%, and is now at $9.94/MMBtu. The propane price increase alone drove up the composite price, as prices decreased for ethane (1.3%), butane (0.7%), isobutane (1.0%) and natural gasoline (0.7%).

click image to zoom

more summary data

Prices/Demand/Supply:

Henry Hub price rises. The Henry Hub spot price rose by 31 cents/MMBtu this week, to $4.66/MMBtu yesterday. Temperatures warmed this week in most of the United States, contributing to price increases that were less pronounced than those seen at Henry Hub. Prices rose slightly at most major markets, with the exception of Boston and Chicago, where spot prices decreased slightly.


click image to zoom

Nymex prices increase 22 cents. After decreasing slightly last week, the Nymex May contract rose this week, from $4.364/MMBtu on Wednesday, April 2, to $4.586/MMBtu yesterday. The 12-month strip (the 12 contracts between May 2014 and April 2015) rose slightly, from $4.454/MMBtu last Wednesday to $4.624/MMBtu yesterday.

Consumption decreases week over week. Warmer temperatures this week contributed to a 4.1% week-on-week decline in total consumption, from an average of 67.5 billion cubic feet per day (Bcf/d) last week to 64.8 Bcf/d this week. This was the second week in a row that consumption decreased, and the lowest weekly average since the beginning of November 2013.

click image to zoom

See the original article >>

Follow Us