Tuesday, September 9, 2014

Big move to come for the EUR/GBP?

By Matt Weller

Much like an elementary student returning to school, European currencies wish they could turn the calendar back to the halcyon days of a few months ago.

Earlier this summer, the uptrends in euro (CME:E6Z14) and sterling (CME:B6Z14) seemed unstoppable, with EUR/USD reaching as high as 1.40 and GBP/USD setting a 5-year high above 1.7100. Unfortunately for euro and sterling bulls though, the two widely-followed currencies have sold off sharply against the U.S. dollar (NYBOT:DXZ14) and other rivals over the last few months.

Aggressive easing measures by the European Central Bank have driven the euro weakness, whereas the pound has been hit by growing concerns that Scotland could declare independence next week. To determine which of these beaten-down currencies is more likely to bounce, traders can analyze the chart of the EUR/GBP cross rate.

As we go to press, the EUR/GBP is testing the top of its 3-month range at .8030. Beyond representing horizontal resistance in late June and mid-August, this level also marks the falling 100-day MA, which the pair has not closed above since all the way back in March. More broadly, the pair remains in a longer-term bearish channel, suggesting that swing traders have been more concerned with the Eurozone’s economic issues than the UK’s Scottish Independence vote.

The daily RSI confirms this view, with the indicator remaining mired in bearish territory (<60) for over a year now. That said it has formed a quadruple bullish divergence at the recent lows, showing that the selling pressure is declining and foreshadowing a possible rally in the coming days.


Source: FOREX.com

Even if Scotland votes for independence on September 18th, prudent technical traders may want to wait for a bullish breakout from the 1-year channel around .8100 and a corresponding breakout in RSI above 60 before growing outright bullish on EUR/GBP. If we do see these developments, bulls may look to target the Fibonacci retracements of this year’s drop at .8137 (50%), .8199 (61.8%), or .8287 (78.6%) next. Meanwhile, a “no” vote (still our favored outcome) could push the pair back down to its 2-year lows at .7880 as traders turn their focus backed to the Eurozone’s entrenched economic concerns. Either way, EUR/GBP should be in for a big move next week.

See the original article >>

Germany offers plan B

By Brian Parkin, Helene Fouquet and Birgit Jennen

Germany and France are poised to take the first step toward a European investment program, as the euro (CME:E6Z14) area’s two biggest economies seek to resolve differences and spur growth without resorting to stimulus spending, government officials said.

The proposals, which enlist the European Investment Bank for loans to companies, aim to pave the way for a €300 billion ($388 billion) investment plan outlined in July, according to three euro-area government officials who asked not to be named because the document is in draft form. Germany and France plan to present the initiative at a meeting of European finance ministers in Milan, Italy on Sept. 12.

Germany’s emerging endorsement marks an attempt to shift the debate away from austerity and acknowledge the European Central Bank’s efforts to prod governments into action to combat low inflation and a weak economic outlook. It’s also intended to deter ECB President Mario Draghi from resorting to purchases of sovereign bonds and asset-backed securities to increase bank lending, a move viewed with anxiety in Germany.

Draghi “threw the kitchen sink” at German Chancellor Angela Merkel, Jacob Funk Kirkegaard, a senior fellow at the Peterson Institute for International Economics in Washington, said in an interview after the ECB’s policy decisions on Sept. 4. “Draghi’s message was plain: my back’s to the wall -- do something to push fiscal stimulus now or watch me buy bonds.”

No Stimulus

With Merkel opposed to fiscal stimulus, German backing for the investment plan requires avoiding pledges of cash and any suggestion that pressure on France and Italy to make their economies more competitive is easing, one official said.

At the same time, the French and German governments aren’t interested in providing state guarantees for Draghi’s asset- purchase program announced last week, according to a draft document obtained by Bloomberg News.

The separate proposal on investment is part of preparations for European Union leaders to discuss growth at a special summit on Oct. 6 and sign off on an investment-boosting plan by the end of the month. Without citing specific projects, the joint paper will refer to an investment gap in Europe in areas such as transportation, broadband and energy, one official said.

The Luxemburg-based EIB would be the favored conduit for investment loans, as outlined in the €300 billion ($388 billion) proposal to “re-industrialize” Europe that designated European Commission President Jean-Claude Juncker presented in July, according to the officials.

Earlier Attempt

Juncker plans to outline the program by February. It would follow a €120 billion growth boost pledged in 2012 that was based on a €10 billion increase in the EIB’s capital and assumptions about how much investment that would unleash.

Germany and France are working on joint proposals to strengthen investment, German Finance Ministry spokeswoman Marianne Kothe said yesterday, declining to comment on details. French government officials didn’t return calls seeking comment.

Pressure on governments is increasing as France’s economy failed to grow in the last two quarters and the government scrapped plans to cut the budget deficit to 4 percent of output this year. Italy is in its third recession since 2008 and Germany’s economy shrank by 0.2% in the second quarter.

Both sides also plan to back national efforts to attract private investors, such as Germany’s bid to harness insurance- industry capital to finance infrastructure projects, the officials said. Cross-border cooperation between national development banks or funds would also be conceivable.

German Model

Merkel’s government touts German development bank KfW Group, the country’s third-biggest lender by assets, as a possible model for other countries. KfW has aided in loans to Greek companies in the wake of the debt crisis, though such an engagement isn’t envisaged in other euro-area countries for now.

KfW development loans “are working well in Greece,” Ralph Brinkhaus, the finance spokesman in parliament for Merkel’s Christian Democratic Union, said in an e-mailed reply to questions. “It makes sense to build up a European development bank model. If supporting companies with tailor-made finance is needed, development banks are the right way.”

Copyright 2014 Bloomberg. All rights reserved. This material may not be published, broadcast, rewritten, or redistributed.

See the original article >>

An Energy-Related Reason Why US Healthcare Outcomes are Awful

by Gail Tverberg

Back in January 2013, the US Institute of Medicine published a report called U.S. Health in International Perspective: Shorter Lives, Poorer Health. This poor health outcome for US citizens is in spite of the US spending twice as much as a percentage of GDP on healthcare as other high-income nations.

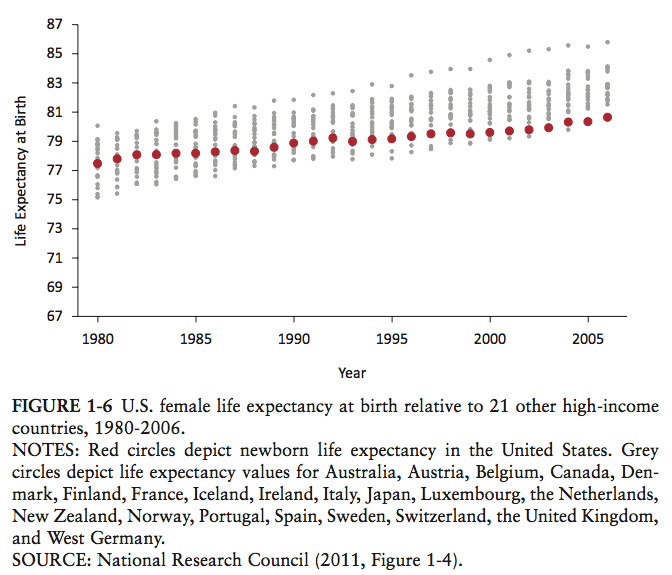
As an example of the problems the US has, the report showed the following exhibit, pointing out that the US has made much smaller advances in life expectancy since 1980 than other high-income nations.  The US is now seventeenth of the seventeen countries analyzed in male life expectancy, and sixteenth out of seventeenth in female life expectancy.

Figure 1-6 Female life expectancy at birth

I am sure I do not know all of the reasons for the US divergence from patterns seen elsewhere, but let me try to explain one energy-related reason for our problems. It has to do with a need to get a wide variety of nutrients at the same time we need to balance (Energy In) = (Energy Needed for Life Processes), in a period of time when the food we eat is increasingly of the “processed” variety. There may also be an issue of eating too much animal protein in our food mix, thanks to today’s ability to ramp up meat production using grains grown and shipped around the world, using fossil fuels.

An Overview of Energy-Related Modifications to Food

If look at primates in general, it is pretty clear that all of the nutrients such animals need come prepackaged in the food that they gather with their limbs. They get the level of exercise they need from gathering this food and from their other daily activities. They have a pretty good balance between (Energy In) = (Energy Needed for Life Processes), without any special effort.

We humans have been modifying food for a very long time, dating back to the days of being hunter-gatherers. Our earliest changes were successful from the point of making humans more dominant. They allowed us to grow larger brains and allowed human population to grow.

The changes made in recent years, thanks to abundant fossil fuels, seem to be excessive, however. The new processed foods are often missing necessary nutrients and fiber, providing mostly empty calories. It becomes a balancing act to get enough of the right nutrients without filling our bodies with calories we don’t need. Some foods (juices, added sugars, very finely ground grains) are sufficiently different from natural foods that our systems don’t react properly to such food. Also, the exercise our body was expecting is often much reduced.

The way our current system works, the food that is closest to its original form is hardest to ship and store, so tends to be highest-priced. The most calorie-dense, over-processed food tends to be cheapest. As a result, the least-educated people (who tend to be poorest) tend to be most damaged by our poor food supply. According to one study, at age twenty-five, men with less than a high school education have a sixteen-year shorter life expectancy than men with a graduate degree.

Remaining Years of Life_prb

Of course, at least part of the problem is the disproportionate lack of health care of less-educated US citizens. There are no doubt effects related to feeling like second-class citizens as well, because of reduced work-opportunities for those with poor educations. But having to work around a poor food system with an inadequate income is an issue that likely plays a major role as well.

How Did Humans Develop Larger Brains? 

There is a popular belief that eating meat made us human. While meat-eating may have played a role, there seem to be other factors as well. National Geographic in an article in the September 2014 issue, The Evolution of Diet, observes that modern day hunter gatherers typically get about 30% of their calories from meat. When meat supplies are scarce, they often live for long periods on a plant-based diet. The article says, “New studies suggest that more than a reliance on meat in ancient human diets fueled the brain’s expansion.”

The point National Geographic mentions is the one I have brought up previously–the theory advanced by Richard Wrangham in Catching Fire: How Cooking Made Us Human. It seems to be the ability to control of fire, allowing humans to burn biomass, which set us apart from other primates. This allowed us to cook food, and in doing so, allowed the food to be more easily chewed and digested. Reduced chewing time freed up time for other activities, such as making tools. Nutrients could be more easily absorbed from cooked food. The fact that the food was easier to chew and digest allowed chewing and digestive systems to shrink, and brains to increase in size. It probably also made it easier for more human children to survive.

Furthermore, we now know that some other primates eat meat, so humans are not unique in this regard. Chimpanzees even hunt animals for their meat. National Geographic reports that baboons eat birds, rodents, and even the young of larger mammals, such as antelopes and sheep. But meat makes up only a small share of their diet. We also know that when monkeys are fed a diet that includes very much meat, they gain weight and experience degenerative diseases like humans.

Food Processing: A Little of a Good Thing vs. Too Much of Good Thing

The experience with cooking some food back in hunter-gatherer days shows that a little help in getting more nutrition from foods can be helpful. Plant cell walls are made of cellulose. Cooking vegetables helps break down these cell walls, making nutrients more accessible. There are other ways of processing food–pounding meat to make it more tender or using a blender to chop it into fine pieces. Humans have been milling grains for a very long time.

But it is easy to overdo the processing of food, especially with the help of fossil fuels. Grains can be ground very finely, far more finely they would have been ground, years ago. Sweeteners of various types can be derived from sugar cane, sugar beets, and corn, and added to products of many types. Parts of fruits and vegetables that are deemed “less desirable” such as skins can be removed, even if these parts have a disproportionate share of the nutrients in them.

There is even a second order kind of change to the food supply that can be put in place. For example, before recent “improvements,” cattle ate a mixture of grasses and digested them in their four-part stomachs that are designed from that purpose. Now cattle are being fed all kinds of foods that are not suitable for their digestive systems, including corn and dried distillers grain, a byproduct of making ethanol from corn. There are many other shortcuts taken, from hormones to antibiotics, so as to produce more meat at less expense. Our bodies aren’t necessarily adapted all of these changes. For one thing, there is much more fat in the beef, and for another, the ratio of Omega 3 fatty acids to Omega 6 fatty acids is badly skewed.

There is the additional issue of whether plants actually contain the nutrients that they did years ago. Many of us have learned Liebig’s Law of the Minimum, which states that plant growth is not controlled by total amount of resources available, but by the scarcest resource. In other words, a plant needs all of its nutrients–just adding more of the most abundant nutrient isn’t good enough. But Liebig’s Law of the Minimum doesn’t remove all deviations in nutrient quantity. Plants will still grow, even if some of the trace elements are present in smaller than the usual quantities. Adding fertilizer (or even crop rotation) does not entirely fix this situation. We still end up with soil that is deficient in some micronutrients. This situation tends to get worse with time, as our sewer systems send human wastes out to sea.

In recent years, we have been hearing more about the role intestinal bacteria play. The processing of our food is especially likely to remove the less digestible portions of our food that these bacteria depend on for their nutrition. This adds yet another dimension to the problem of food that deviates from what our bodies are expecting us to eat.

Thanks to fossil fuels, processing of all kinds is cheap. So is adding sugar, artificial colors and artificial flavors to help cover up deficiencies in the original crop. The shortcuts farmers take, including heavy use of fertilizers and pesticides, are ways to produce food more cheaply. The food we end up with is inexpensive and convenient, but doesn’t necessarily match up well with what human digestive systems are adapted to.

What Kind of Exercise Do We Need?

The story I keep reading is that we need a certain amount of high-intensity intermittent exercise to help our bodies operate as they are intended to. Running for even an average of five or ten minutes a day is said to reduce cardiac causes of death by 30% to 45%, and to increase overall life expectancy by three years. We can easily imagine that hunter-gatherers quite often needed to sprint from time to time, either to avoid predators or to catch potential prey. The finding that human beings need short bursts of high intensity exercise, such as running, would seem to be consistent with what our ancestors did. We also can’t sit for long periods–something our ancestors didn’t do either.

How about strength training? One thing that occurred to me when I visited India is how unnatural it is to have chairs to sit on. Much of the world’s population, even today, sits on the ground when they want to sit down. Needless to say, people who don’t sit on chairs get up from the floor many times a day. This is a type of fitness training that we in this country miss. We in the West also don’t squat much–another type of fitness training.

Even with the beneficial effects of exercise, some researchers today believe that food plays a more important role than exercise in obesity. (Obesity is linked to ill health and shorter life expectancies.) A recent study by Herman Pontzer and others compared the energy expenditure of the Hazda hunter-gatherers to Westerners. The study found that average daily energy expenditure of traditional Hazda foragers was no different from that of Westerners, after controlling for body size. The body seemed to compensate for higher energy expenditure at times, with lower energy expenditure at other times.

Conclusion

It seems to me that our appetites don’t work correctly when we fill ourselves with overly processed foods that are lacking for essential nutrients. We don’t stop eating soon enough, and we quickly feel hungry again. In part this may be from eating foods highly processed foods that would never be found in nature; in part it may be because the foods are missing the micronutrients and fiber that our bodies are expecting. Low-income people especially have a problem with such diets, since diets rich in fruits and vegetables are more expensive.

Many people believe doctors can fix our health problems. Looking across countries, diet and public health issues tend to be much more important than the medical care system in the health of a population. With most chronic health conditions, doctors can only take bad health situations and make them somewhat better. High rates of illness and increased mortality remain, similar to what we see in the United States.

Many of us have heard about the so-called calorie restriction diets of monkeys. This is a misnomer, in my view. In at least one version of it, it is a comparison of monkeys fed a low calorie diet that provides a wide range of nutrients found in vegetables, with a diet typical of Americans. If, in fact, we humans also need a wide range of nutrients found in vegetables, we should not be surprised if we have similarly poor health outcomes.

NYT 31aging_graphic_lg

According to the graphic, Owen, 26, is affected by arthritis. His skin is wrinkled and his hair is falling out. He is frail and moves slowly. His blood work shows unhealthy levels of glucose and triglycerides. Canto, 25, is aging fairly well.

I personally have been eating a diet that is close to vegetarian for twenty years (heavy on vegetables, fruits and nuts; some fish and diary products; meat only as flavoring in soups). I also cut way back on processed foods and foods with added sugar or corn by-products. When I first changed my diet, I had a problem with arthritis and was concerned that I was at high risk for Type II diabetes. I lost weight, and my arthritis disappeared as did my blood sugar problems. In fact, I rarely have reason to visit a doctor. In many ways, I feel like Canto on the left.

As I pointed out at the beginning of the post, we need to get a wide variety of nutrients at the same time we need to balance (Energy In) = (Energy Needed for Life Processes). Back in hunter-gatherer days, this was easy to do, but it is increasingly difficult to do today. Besides cutting back on processed foods, eating a diet at that is low in meat may be a way of doing this. Studies of people who eat mostly vegetarian diets show that they tend to have longer life spans. There is also direct evidence that diets that are higher in animal protein tend to shorten life spans. These findings don’t necessarily correlate with studies of what works best for losing weight, which is what most people are concerned about in the short term. Thus, we are deluged with a lot of confusing findings.

Food and health problems are issues that tend to strike a nerve with a lot of people. I can’t claim to be an expert in this area. But stepping back and looking at the issue more broadly, as I have tried to do in this article, can perhaps add some new perspectives.

See the original article >>

Commodities fight weak fundamentals/strong dollar

By Phil Flynn

The Dominate Dollar

While the fundamentals for petroleum oil are very weak there is more to the markets’ recent weakness. You can’t ignore the impact of the soaring dollar. Commodities across the board are finding it harder to try to establish support as currencies in Europe continue to get crushed. Not only has the euro, which has been hit by the ECB's quantitative easing but the British pound Sterling that has been rattled with the possibility of Scottish independence. Even with the positive news from an oil demand standpoint that the EU will delay sanctions on Russia as they try to determine that a cease-fire might hold failed to overcome the strength in the dollar.

Brent crude hit the lowest level since May of 2013 as demand prospects continue to look bad. Libya is even calling on Saudi Arabia to cut production as their oil comes onto the market adding to a growing glut. U.S. gasoline demand on the four-week moving average was the worst since the early part of the decade signaling that perhaps the bad jobs report was not a fluke. Scottish independence also makes the outlook for oil murkier. An independent Scotland would have to find a way to support itself and they would have to find a way to develop their energy resources. The oil demand numbers are sending warning signs that the global economy is slowing. The deflationary problems in Europe seem to be spreading. At this point it is not clear whether the ECB has done enough to stimulate the economy but if oil demand is any indicator there may be more headwinds for the economy.

This of course will make the Federal Reserve’s job more difficult as a weak jobs number and weak oil demand is signaling that we may see the economy starting to contract a bit.  Yet we are still the best house in a bad neighborhood and the dollar is adding to deflationary numbers on the commodity front. Commodities are getting crushed from sugar to coffee to gold to grains. The dollar is the major force not to mention sinking demand expectations around the world.

Natural gas snapped back(NYMEX:NGX4) as warm temperatures that last two weeks and cooler temps ahead could slow the injection march. We also have a reminder that we are still in Hurricane season. The National hurricane center is reporting that a broad area of low pressure located a few hundred miles south of the Cape Verde Islands continues to produce disorganized showers and thunderstorms.  Environmental conditions are forecast to be conducive for gradual development of this disturbance during the next several days while it moves west-northwestward at about 15 mph.  The MHC says the storms formation chance through 48 hours is at a medium 30% and the formation chance through five days at a 60% chance.

See the original article >>

Crude oil breaks out, pulls back, could go much lower

By Matt McKinney

Fundamentally, I think the Hightower morning commentary that I read in our web application MARKETHEAD summed up the whole action in crude oil over the last 14 hours very well.

It stated frankly that, "October Crude Oil prices fell to a new 7-month low during the initial morning hours, weighed down by Chinese economic data overnight showing another drop in import activity. This stoked slowing economic growth concerns and comes on the back of disappointing US Non-Farm Payroll data late last week. An added headwind for the crude oil market came with strength in the U.S. dollar, which is notably higher from weakness in the British Pound.

So far, the crude oil market has shown little concern toward reports of rising violence in Eastern Ukraine that breached a temporary ceasefire put in play late last week with pro-Russian separatists. Friday's softer August Non-Farm Payroll report served to raise concern over the current growth trajectory and stoked oil demand concerns." Really what more can I say. This is the kind of information that I find on a daily basis and you can too right here.


Crude oil, November, daily

Technically, on the chart above I have placed my favorite technical indicators. They are the 9-day Simple Moving Average (SMA, red line), the 20-day SMA (green line), and the 50-day SMA (blue line). I have also added the Bollinger Bands (BB's, yellow lines) and Candlesticks (red and green bars), each bar represents one day of trading on these daily charts.

This particular formation and the way my indicators are lining up shows me that this market may go sideways for a while. With a high of around $95/barrel and a low of around $92/barrel. That was the case until today when we made a new low today/overnight (9/8/14) for the move and even though we closed back near my range, I believe once a market has made a move like this, it will go back to that price in short order. So I look for a new low close in the crude.

Options play:

Since I see crude prices moving lower from here a play could be to buy put options or bear put spreads with a call for a hedge in a 3 to 1 ratio just in case the trend changes dramatically to the upside. Another play could be to sell deep out of the money calls collecting premium. Remember selling naked options involves unlimited risk and should only be considered if you have a well-funded account.

For exact details on other types of risk, months, expiration dates, strike prices, and number of positions feel free to contact me at 312-277-0115 or mmckinney@zaner.com. In addition, I am by no means "married" to the silver market. I like to make trade recommendations to my clients in the direction of the existing trend whether the market be the precious metals, energies, currencies, financials, softs, grains and more.

See the original article >>

Dot Com Bubble 2.0—–Lunacy By The Numbers

by David Stockman

Thanks to the money printing mania of the world’s central bankers, the Wall Street casino has gone global. Accordingly, mindless speculation and momentum chasing have reached new absurdities, as exemplified by the red hot roster of international high flyers below.

The financial data for the top name on the list, Twitter, is all that is required to remind us that once again markets are trading in the nosebleed section of history, rivaling even the madness of March 2000. Currently, Twitter (TWTR) is valued at $31 billion.That’s 18X revenue, but the catch is that the revenue in question is it’s lifetime bookings over the 18 quarters since Q1 2010.

When it comes to profits, the numbers are not nearly so promising!  For the LTM period ending in June, TWTR booked $974 million of revenue and $1.7 billion of operating expense. That why “NM” shows up in its LTM ratio of enterprise value to EBITDA. It turns out that its EBITDA was -$704 million. In fact, its R&D expense alone was 83% of revenues.

That’s not the real fantasy, however. The sell-side hockey sticks indicate that TWTR’s forward multiple is only 86.6X projected EBITDA.  Let’s see. At its current total enterprise value, this implies it will generate $350 million of positive EBITDA in the next 12 months—or a $1 billion favorable swing from the LTM number.

Just say its going to take some doing—not to say a miracle. During Q2 EBITDA was -$104 million compared to -$13 million in the year ago June quarter. So TWTR’s cash profit numbers are marching to the rear at a furious pace, but never mind. It’s EBITDA will soar skyward any moment now, making it 86.6X forward multiple completely rational….. Right.

Needless to say, this kind of speculative lunacy would never occur on the free market under a regime of honest price discovery. Yes, markets would discount at hefty multiples the future value of unusually promising and innovative enterprises with demonstrated capacity to convert revenues into profits.

Thus, a 5% free cash flow yield might make sense for an especially solid and promising new enterprise. In that event, a $31 billion market cap would require EBITDA less CapEx in the range of $1.6 billion. Alas, it is not clear that TWTR will ever even generate that much revenue, let alone free cash flow—of which, so far, it has generated exactly none.

So the list below is mainly a throw-back to the dot com mania. Today’s equivalent of eyeballs are now being discounted at absurd multiples. In the case of TWTR, its valuation is being driven by hundreds of millions of account holders—a significant fraction of which are fake.

And perhaps that is the appropriate metaphor. The wild valuations shown below are the product of a fake market—a pure gambling casino that is being fueled by a worldwide money-printing craze that has no precedent in recorded history.

The cynic is likely to say, so what? The gamblers will take their lumps, and probably soon enough. But its not that simple. The serial bubbles created by the central banks cause vast malinvestments and deformations—-economic distortions which confer stupendous, unearned windfalls on some and arbitrary, wanton losses and penalties on others.

Just consider the implications of TWTR’s LTM financials. Its SG&A expense for that period was $657 million or about $350,000 per average employee over the period. Needless to say, this tsunami of money is not being earned from sales; its being burned from the proceeds of serial capital raises that have accompanied the skyward ascent of TWTR’s valuation in the venture capital and post-IPO casino.

As for the windfalls, the gigantic, if temporary, gains of options holders are obvious enough.  But how did the average price of a home in San Francisco rise to north of $1 million? How is it that moderate income tenants are being flushed out of rental units via every lawyer’s trick in the books? Why are traditional small businesses throughout the city closing-up shop owing to soaring commercial rents?

Any day now, this third and greatest bubble of the 21st century will reach a boiling point that even the mad money printers in the Eccles Building will not be able to sustain. Then there will be another thundering financial market crash—with collateral damage being ricochet willy-nilly in every direction along main street.

And that’s the real evil of Keynesian central banking. During the extended process of bubble inflation, the free market’s normal mechanisms which check unbridled speculation—such as short-selling—are disabled and eventually banished from the casino. Accordingly, bubbles grow to elephantine magnitudes under the malignancy of free money carry trades and one-way markets. In their wake, they channel massive flows of capital and real resources to blatantly uneconomic and often destructive purposes.

At the end of the day, free money is the mortal enemy of free markets. And free money is the catalyst for rank speculations that value imaginary cash flows at 87X…..that is, before the high flyers came crashing back to earth, like they always do.

See the original article >>

Follow Us