Wednesday, June 15, 2011

Global PMI Signals Economic Pickup (Guest Post)


Despite the markets showing their dismay when the manufacturing PMIs for May were published, the pace of expansion in the global economy has actually picked up!

The JPMorgan Global Composite PMI, which takes the manufacturing and non-manufacturing/services into account, rose to 52.6 from 51.8 in April (a number above 50 indicates expansion) as the turnaround of Japan since the twin disaster seems to be lending solid support.


Sources: ISM, Markit, CFLP, Plexus Asset Management.


GDP-weighted/ Composite PMI Direction


Rate of change
Country May-11 Apr-11
US*** 54.3 54.6 Growing, robust Slower
Eurozone**** 55.2 57.1 Growing, robust Slower
Germany* 57.1 59.2 Growing, robust Slower
France* 60.3 62.4 Growing, robust Slower
UK**** 53.3 54.4 Growing Slower
Japan* 46.2 35.0 Contracting Significant improvement
Emerging economies


China** 57.9 58.7 Growing, robust Slower
Brazil* 53.0 52.5 Growing Faster
India* 57.7 60.7 Growing, robust Slower
Russia* 55.4 55.4 Growing, robust Slower
Hong Kong* 52.2 52.9 Growing Slower
UAE* 56.0 57.5 Growing, robust Slower
Saudi Arabia* 62.6 62.7 Growing, robust Slower
JPMorgan Global Composite* 52.6 51.8 Growing Faster


Sources: *Markit; **CFLP, Li & Fung, Plexus Asset Management; ***ISM, Plexus Asset Management; ****Markit, Plexus Asset Management.

The contraction in Japan has eased significantly, with the Markit composite PMI jumping to 46.2 from 35.0 in April. Growth in the US eased slightly with my ISM GDP-weighted composite PMI registering 54.3 compared to April’s 54.6. The manufacturing and non-manufacturing PMIs reversed roles – the non-manufacturing PMI jumped to 54.6 from 52.8 while the manufacturing PMI sank to 53.5 from a very robust 60.4.

Growth in the Eurozone’s economy at long last eased with my GDP-weighted PMI coming in at 55.2 compared to 57.1 in April. Although the pace of growth in both Germany and France has eased, these countries continue to find themselves growing at a rapid pace. Elsewhere the pace has eased somewhat in China, the UK, Hong Kong and India.

Except in the case of Japan, where the manufacturing sector expanded again after reeling in the face of the twin disaster, growth in the global manufacturing sector has eased significantly. My GDP-weighted manufacturing PMI for the major economies dropped by 2.4 points to 53.1 in May.

The USA’s manufacturing sector was hit the hardest, succumbing 6.9 index points, followed by Germany’s 4.3 and the Eurozone’s 3.4 index point declines. The manufacturing sectors in the Eurozone’s problem countries are struggling, though.

The contraction in Greece has deepened, Spain has moved into contraction while Ireland’s PMI fell heavily from 56.0 to 52.1. China’s CFLP manufacturing PMI was in line with my earlier expectations based on seasonal weakness. Brazil was the only economy that managed to eke out a faster rate of expansion.


Manufacturing PMI


Direction


Rate of Change
Country May-11 Apr-11
US***** 53.5 60.4 Growing Slowed significantly
Eurozone* 54.6 58.0 Growing Slowed significantly
Germany* 57.7 62.0 Growing, robust Slowed significantly
France* 54.9 57.5 Growing Slowed significantly
Greece* 44.5 46.8 Contracting Deeper
Italy* 52.8 55.5 Growing Slowed significantly
Spain* 48.2 50.6 Contracting From growing
Ireland* 51.8 56.0 Growing Slowed significantly
U.K.* 52.1 54.6 Growing Slowed significantly
Japan* 51.3 45.7 Growing From contracting
Australia* 47.7 48.4 Contracting Deeper
Emerging economies


Brazil* 50.8 50.7 Growing, weak Faster
China** 52.0 52.9 Growing Slower
Czech* 55.9 59.0 Growing, robust Slowed significantly
Poland* 52.6 54.4 Growing Slower
Turkey* 50.6 52.7 Growing, weak Slowed significantly
India* 57.5 58.0 Growing, robust Slower
Russia* 50.9 52.1 Growing, weak Slower
Taiwan* 54.9 58.2 Growing Slowed significantly
RSA*** 55.1 56.4 Growing, robust Slower
S Korea 51.2 51.7 Growing Slower
Global**** 53.1 55.5 Growing Slowed significantly

Sources: Markit*; Li & Fung**; Kagiso***; Plexus Asset Management****; ISM*****.


Sources: Markit*; Li & Fung**; Plexus Asset Management****; ISM*****

Non-manufacturing/Services PMIs

The JPMorgan Global Services PMI for May jumped to 52.5 from 51.0 in April. The US ISM non-manufacturing PMI retraced 1.8 index points of the 4.5 index point drop in April.


Sources: ISM, Markit, CFLP, Plexus Asset Management.


Non-manufacturing/ Services PMI
Direction

Rate of Change
Country May-11 Apr-11
US** 54.6 52.8 Growing Faster
Eurozone 55.4 56.7 Growing, robust Slower
Germany 56.1 56.8 Growing, robust Slower
France 62.5 62.9 Growing, robust Slower
Italy 50.1 52.2 Growing Slowed significantly
Spain 50.9 50.4 Growing Faster
Ireland 50.5 50.2 Growing Faster
UK 53.8 54.3 Growing Slower
Japan 43.8 35.0 Contracting Improved significantly
Australia 49.9 51.5 Contracting From expanding
Emerging economies


Brazil 53.3 53.2 Growing Faster
China* 61.9 62.5 Growing, robust Slower
India 57.7 59.2 Growing, robust Slower
Russia 57.6 55.8 Growing, robust Faster
JPMorgan Global Services
52.5

51.0

Growing

Faster

Sources: Markit; CFLP*; ISM**; Plexus Asset Management.

The Eurozone PMI dropped by 1.3 index points to 55.4 from 56.7 in April, with the countries other than Germany and France taking the biggest knocks. Growth in Italy’s services sector has decelerated sharply, whereas Spain and Ireland continue to find themselves on the brink of contraction. Growth in the UK’s services sector eased slightly to 53.8 from 54.3 in May.

The pace of contraction in Japan has eased significantly by 8.8 index points to 43.8 in May from 35.0 in April. Australia’s services sector is contracting again.

Brent crude oil reaches $21 premium over WTI


China's hot but some like it hot.
 
Well the one good thing you can say about inflation in China, at least it did not come in a 6%. The Chinese consumer inflation number hit a sizzling 5.5% in May, far short of the whisper number up which seemed to be topping 6%. Still the Chinese government wasted no time in raising the reserve requirements on their banks by a half a point to show that they are less than pleased with the overall inflation direction. Some data coming out of China is showing some softening, especially a surprising report on China crude oil consumption that confirms some industrial demand slowdown in China may be taking its toll on oil demand. According to a report by the National Development and Reform Commission as reported by Bloomberg News, Chinese daily consumption of gasoline, diesel and kerosene dropped to 650,000 metric tons in May. Monthly consumption gained 5.2 percent from a year earlier to 20.19 million tons, with China using 5.82 million tons of gasoline, up 7.5 percent, and 12.84 million tons of diesels up 3.9 percent.

In yesterday's session, demand destruction fears permeated trading yet supplied fears of high quality crude coveted by European refineries blew out the Brent Crude and the West Texas Intermediate oil to an all time high. The strength in the Brent reflects the ongoing loss of high quality Libyan crude and fears of its recent replacement Nigerian bonny light. As reported by Reuters News, "Brent crude rose on Monday to its highest price in more than five weeks, pushing its premium to U.S. benchmark crude past $21 a barrel, a record, as a force majeure in Nigeria further strained a tight European market. Brent's premium to U.S. crude rose another $1.50 a barrel after hitting a series of record highs last week. Traders cited a host of bullish factors in Europe, from Libya's prolonged outage to limited supplies of North Sea benchmark Forties crude. A fresh catalyst emerged on Monday when Royal Dutch Shell declared force majeure on its Nigerian Bonny Light crude oil loadings for June and July. Shell blamed production cutbacks caused by leaks and fires on its Trans-Niger Pipeline. Brent crude for July delivery rose 85 cents to $119.63 a barrel by 11:54 a.m. EDT. .S. July crude fell 80 cents to $98.49 barrel, having slipped as low as $97.81." "The Shell force majeure explains some of the Brent strength and even though there is crude around, it's a question of quality," said Phil Flynn, analyst at PFGBest Research in Chicago. "U.S. crude supplies are ample and there are still concerns about the lack of Libyan (sweet) crude and Saudi intentions to raise output doesn't solve the problem for European refiners because the Saudi crude is sour," Flynn added. U.S. gasoline and heating oil futures were supported by the strength of the Brent contract, which has pushed domestic sweets like Light Louisiana Sweet to big differentials above the benchmark U.S. light sweet crude contract."

Still despite those fears both Brent Crude and WTI took a hit on more fears about Greece after the Standards and Poors. As reported by Bloomberg News, "Greece had its credit rating cut by three levels to CCC by Standard & Poor's and the rating company said the nation is "increasingly likely to restructure its debt." A restructuring would likely, "result in one or more defaults under our criteria," S&P said in a statement today. "Risks for the implementation of Greece's EU/IMF borrowing program are rising, given Greece's increased financing needs and ongoing internal political disagreements surrounding the policy conditions required by Greece's partners." The downgrade comes as the European Central Bank and Germany battle over how to bail out Greece and whether officials should push creditors to share some of the costs. ECB President Jean-Claude Trichet said today that his advice to European governments is to "avoid what would be a compulsory concept "and "avoid whatever would trigger" a default. The outlook on the rating is negative, S&P said. The rating company held its recovery rating at '4,' indicating it estimates bond holders would recover 30 percent to 50 percent of their investment. A "financing gap has emerged in part because Greece's access to market financing in 2012 and possibly beyond, as envisaged in the current official EU/IMF program, is unlikely to materialize," the report said.

It looks like crude oil is in a choppy downtrend to perhaps the mid eighties! Yes, you heard it here first! Forget all those Jonny come lately's!

Tuesday, June 14, 2011

U.S. Macro in Three Charts: Credit Flows

By Global Macro Monitor

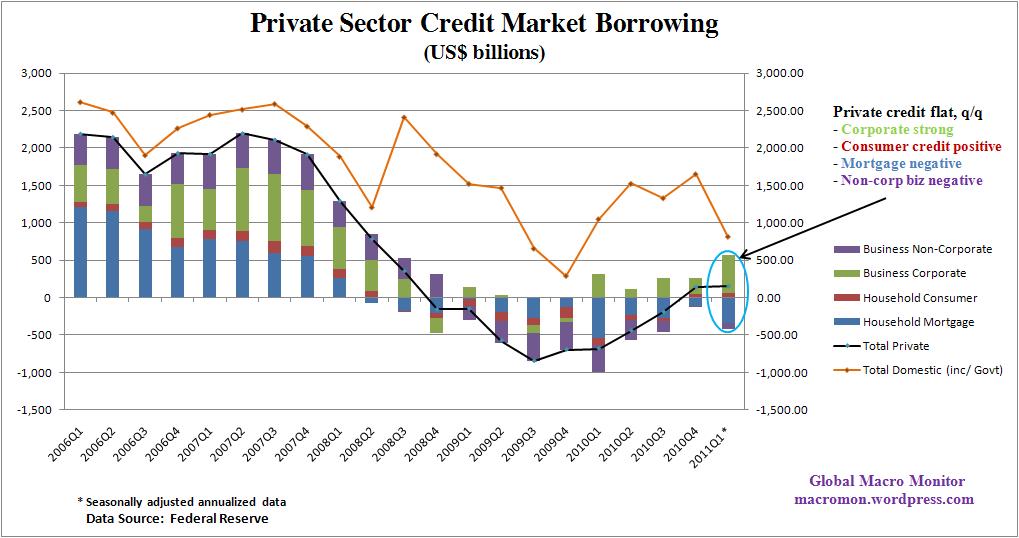
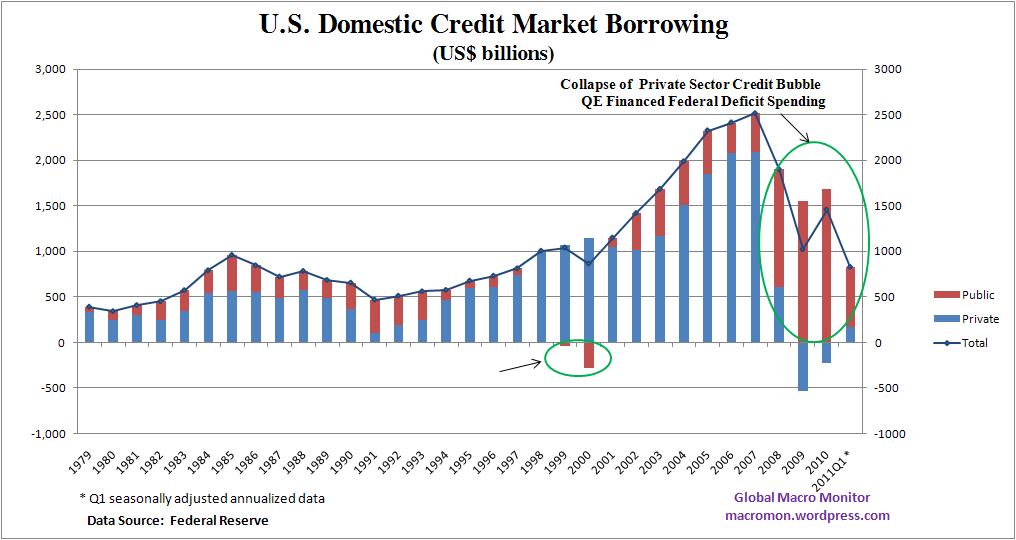
The U.S. is suffering from insufficient aggregate demand the result of the bursting of the 2004-07 credit bubble. The consumer led economy financed by borrowing, much of it backed by home equity, has given way to massive private sector deleveraging as reflected in the charts below. To cushion the blow, the federal government stepped up deficit spending in an effort to replace the decline in demand. This is clearly illustrated in the charts below.

The latest data from the Federal Reserve’s Flow of Funds Accounts show that private domestic credit borrowing of the non-financial sector is still at very anemic levels (see middle chart) . Though total private non-financial credit growth was flat in Q1, corporate continued to strengthen and consumer credit was positive for the second straight quarter. This was offset, however, by continued deleveraging in the mortgage and non-corporate business sector. The negative borrowing is likely both supply and demand constrained.

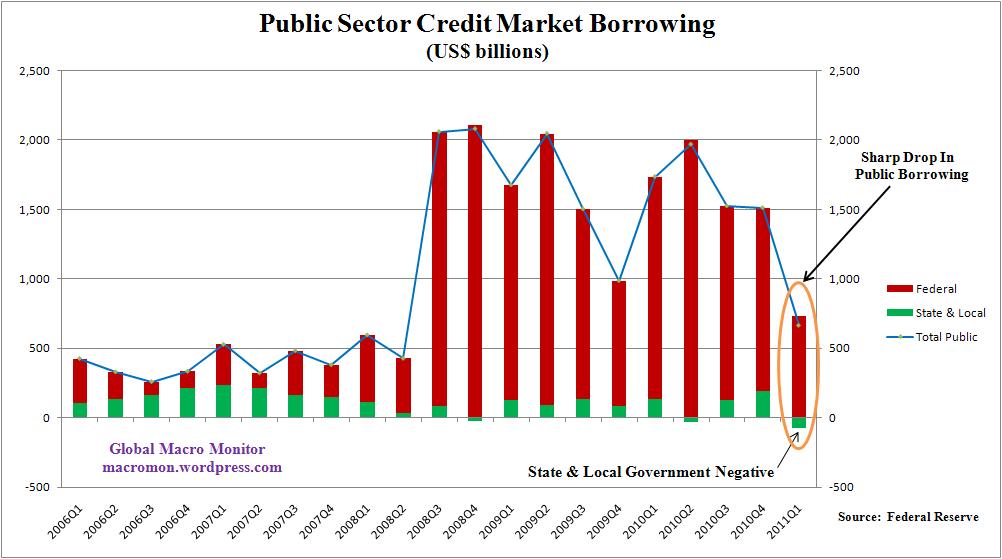
The charts are revealing as they also illustrate the sharp Q1 drop in public sector borrowing with state and local government turning negative. Unless private credit significantly improves — net mortgage lending turning positive, for example – to help finance the expansion of domestic demand, the economy will likely remain sluggish as the crunch in public spending continues. After all, President Obama did say that “the flow of credit is the lifeblood of our economy.”

Corporate spending and the export sector will have to do the heavy lifting as the U.S. works its way through the credit mess. The President needs a positive Black Swan event, such as the explosion of the internet, which drove high levels of investment spending during the Clinton Administration, for example.

Policies to free up financing for small and non-corporate businesses and renewed efforts to clean up mortgage sector, which also allow housing prices to bottom, could help strengthen the recovery. Stay tuned, we’ll be back with more analysis of the Flow of Funds.

~~~

~~~


See the original article >>

“US Debt Default Would Be a Moral Disaster”

by John Fullerton

So declared JPMorgan CEO Jamie Dimon regarding the prospect of a US default on its debt, after which he received a standing ovation at the University of Colorado’s Denver School of Business. Hmm… Let’s do a little press review—the following items quoted from recent news articles:
  • JPMorgan Chase recently lost a class-action lawsuit brought upon the bank for illegally foreclosing on military members’ homes while they were on active duty.
  • J.P. Morgan had declined to address the matter until Wednesday. But in a sworn deposition, one of the bank’s employees, Beth Ann Cottrell, admitted that she and her team signed off on about 18,000 foreclosures a month without checking whether they were justified.
  • The federal bankruptcy court judge presiding over the Bernard Madoff case has revealed the JPMorgan Chase employees who allegedly suspected they were doing business with a Ponzi schemer.
  • J.P. Morgan Chase agreed to a $722 million settlement with federal regulators over accusations that the bank and two former executives made illegal payments to win municipal bond business from Jefferson County, Alabama.
  • Deutsche Bank AG, JPMorgan Chase & Co., UBS AG and Hypo Real Estate Holding AG’s Depfa Bank Plc unit were charged with fraud linked to the sale of derivatives to the City of Milan.
  • JPMorgan Chase is being sued by Allstate insurance company for fraud, in the latest example of a big bank being accused of knowingly selling a poor-quality product.
  • The lawsuit alleges that J.P. Morgan Chief Executive James Dimon and other top executives used inside knowledge to take advantage of Lehman as its financial state worsened. J.P. Morgan, the suit alleged, coerced Lehman to turn over $8.6 billion in collateral in September 2008, triggering a liquidity squeeze that contributed to Lehman's collapse.
  • The latest settlement brings J.P. Morgan's total bill to settle regulatory and other lawsuits related to its role in the Enron collapse to more than $3.3 billion, including the $2.2 billion the bank agreed to pay in the class-action lawsuit that has the University of California as the lead plaintiff.
  • A former JPMorgan Chase & Co. banker pleaded guilty to rigging bids for municipal-bond investment contracts, becoming the eighth person to admit joining the biggest conspiracy in the $2.8 trillion market’s history.
These settlements and allegations (and there are more) collectively paint an unattractive picture of the firm I dedicated 18 productive years of my life to (although it bore no resemblance to the JPMorgan of 2011).

And this is the picture of the bank headed by America’s “least hated banker” according to the New York Times. It’s a bank whose dividend has been slashed, and whose stock price has not once seen the high fifties it was trading at when I left ten years ago. This is also despite massive implicit and explicit government subsidies worth billions over that time, a derivative book that has ballooned to a ludicrous $87 trillion in notional contracts outstanding that provides unchecked oligopoly power and alone makes the firm too big to fail and impossible to liquidate in an orderly fashion no matter what Dodd-Frank would like us to believe, a business model that would fail if true resiliency inducing capital reserves and liquidity mismatch limits were demanded by regulators not captured by the banking lobby, and grotesque compensation going to senior management along the way despite all its legal and ethical challenges and business failures.

As I contemplate unemployment of nearly 10% in the United States and far worse in places like Greece, Iceland and Ireland, made worse by crushing austerity, the violence and permanent human damage it represents, unemployment and underemployment of college graduates 25 and under of nearly 50% in the US, layoffs of good teachers in already failing schools, the economic induced suicides, the universal stress, all part of the rolling fallout of the finance-triggered Great Recession, I’m left with a simple question:

What exactly constitutes “moral disaster” Mr. Dimon?

CREDIT SUISSE: LOW RATES AND ECONOMIC UNCERTAINTY ARE BULLISH FOR GOLD

by Cullen Roche

Credit Suisse says the recent economic uncertainty only strengthens the bull case for gold as investors are likely to turn to the precious metal as a safe haven. They maintain that the economy uncertainty will force the Fed to remain very accommodative. This potent mix of uncertainty and low real interest rates creates a very bullish outlook for gold prices:
“Low real interest rates should attract further investment demand for gold. Gold should also benefit from rising uncertainty over the economic outlook.
Gold to benefit from low yield environment. Precious metals benefit from the low yield environment. In particular, gold is less cyclical than other commodity markets and should perform well in the weeks ahead.”

See the original article >>

How Texas drought helps US cotton Futures

By Chuck Kowalski

Cotton growing areas in Texas are facing very hot, dry conditions and signs point to a lower than expected cotton crop thus far in the U.S. Texas is the largest cotton growing state in the country, so losses could be significant if the weather doesn't turn soon.

Someone who hasn't been following the cotton market for the last year might get very excited about this news. However, there is another side of the equation - as there always is. When we look at the world supply and demand picture, it gets cloudier.

Exports are getting weaker with a great deal of cancellations in recent weeks. You can imagine how some buyers might be inclined to cancel their orders for cotton from March when the price was around $2.20 a pound and now it is less than $1.50.

There are also more worries about a slowing U.S. economy as well as China trying to slow their economy. China and India are also expected to expand their cotton production in the upcoming season - the first and third largest cotton producers in the world, respectively.

Cotton is under pressure this week, as it is an economically sensitive commodity. The recent weakness in the stock market creates a tough headwind for cotton. December cotton, which is the new crop contract, is trading at $1.3050 a pound.

The market fell just below 1.15 in May and I would expect that to be a good value area for cotton. I wouldn't expect prices to fall much below there as long as drought condition prevails for cotton crops in Texas. If sentiment for the global economy turns for the better and stocks rally, cotton could have a nice rally.

Corn futures managed to set another record high even though many other markets were feeling pressure on Friday. July corn futures missed touching the $8 mark by one tick and are currently trading at $7.96 a bushel in the early afternoon.

Corn received more confirmation from the USDA yesterday that supplies are getting tighter for corn in the U.S. and globally. The USDA is now estimating demands to be 55 million bushels greater than production this year.

They removed 1.5 million acres of planted acres from the equation due to weather problems, but many analysts believe that number will grow. There were more than 5 million acres yet to be planted just a few days ago. They could get planted in time, but the odds are against them.

Corn acreage is being revised lower and now we have to worry about yields. More than 20 percent of the corn crop wasn't planted by May 22nd. Yields for corn tend to drop if it isn't planted by late May and especially in June. If things remain constant, yields will probably come in lower than estimated. Weather this season will be as important as ever.

More wet weather in the Midwest over the next week will cause problems with getting the final acres planted. Extreme heat in July could whip the markets into a frenzy as corn goes through its critical pollination phase. Heat stress at this time can reduce yields significantly.

There is also the chance that weather could be spectacular for the season and yields could be revised higher. For now, corn traders know there is no room for error this season and prices tend to rise under these conditions.

Follow Us